


Gas price: Ukraine and Europe. Market overview
Over the last week, natural gas prices in Ukraine were stable, with minor bilateral fluctuations.
Ukrainian Energy Exchange
Last week, trading in October and November 2024 continued. In total, 8 companies formed positions for the purchase and sale of natural gas: D.Trading, Ukrnafta, Ukrnaftoburinnya, Nadra-Geoinvest, GTS Operator of Ukraine, GPK Oil and Gas Trading, JV BNK, and Electro-Gas.
The starting prices of resources were growing throughout the week. As a result, as of Friday, the average starting price of October resources in the GTS was 0.30% higher than on Monday.
Last week, both sell and buy positions were sold. In total, 40,600 thousand cubic meters of natural gas were sold. Of this amount, 18,000 thousand cubic meters of November’s resource in the GTS were sold by Ukrnafta and 17,200 thousand cubic meters of October’s resource in the GTS were purchased by the GTS Operator of Ukraine.
The quotation prices formed as a result of the auction are shown in the chart below.
On the short-term natural gas market of the UEEX, participants formed bids in the GTS and UGS. No significant price fluctuations were recorded during the week. The weighted average price of the CPO on Friday, October 11, amounted to UAH 14,550 excluding VAT.
European market
At the beginning of last week, European gas markets experienced a geopolitically driven growth. Developments in the conflict in the Middle East have raised concerns about supply. However, European reserve levels remain high, limiting price growth.
As for the settlement prices of TTF gas futures on the ICE market on the Front-Month, during the second week of October they continued the upward trend of the previous week.
The correlation between NBP Day-Ahead and TTF changed last week, and the day before last week’s discount turned into a premium on October 7. Last Friday, the UK maintained a premium of 0.31 p/term over the European index, encouraging imports from continental Europe to the UK. British short-term gas prices on Thursday mostly recovered their midweek losses, with the NBP spot price rising by almost 5% to close at 98.50 p/therm. The increase was driven by colder weather forecasts for the weekend and a reduction in wind generation. The Sum-2025 contract also rose by more than 4% to close at 95.52 p/therm as geopolitical tensions and lower LNG exports to the UK added to the pressure.
Prices of contracts with delivery in the relevant period, EUR/MWh, 10.10.2024
| Instrument | THE | CEGH | TTF | TGE/POLPX | CEEGEX/HUDEX | Average price |
|---|---|---|---|---|---|---|
| Day1 | 40,33 | 39,6 | 39,71 | 40,36 | 37,32 | 39,46 |
| M+1 | 40,99 | 40,54 | 40,24 | 40,76 | 39,38 | 40,38 |
| Q +1 | 41,7 | 41,68 | 40,99 | 40,67 | 41,19 | 41,25 |
| S +1 | 39,94 | 40,55 | 38,9 | 35,33 | 38,79 | 38,70 |
Month-ahead contracts at all the analyzed hubs showed the same trend in terms of spot prices, with an average increase of 2.37%. Quarterly forward prices were 4.60% higher than spot prices on average. Season-ahead prices with an average value of EUR 38.70/MWh tended to decrease by an average of 1.83% compared to spot prices.
The November futures for LNG in Asia, the JKM Platts Future index, settled last Thursday at USD 468.09 per thousand cubic meters. Asian demand for 2025 is expected to grow rapidly with a new stimulus package in China, which will help the economy and real estate sector, as well as Southeast Asia in increasing LNG imports.
Northwest European LNG market players are raising their stakes to remain competitive on the global stage. The LNG North West Europe Marker closed last Thursday at USD 434.97 per thousand cubic meters. Traders see an increase in the purchase price to attract flows to the continent from other competitive demand centers, such as Asia, Egypt, and Brazil.
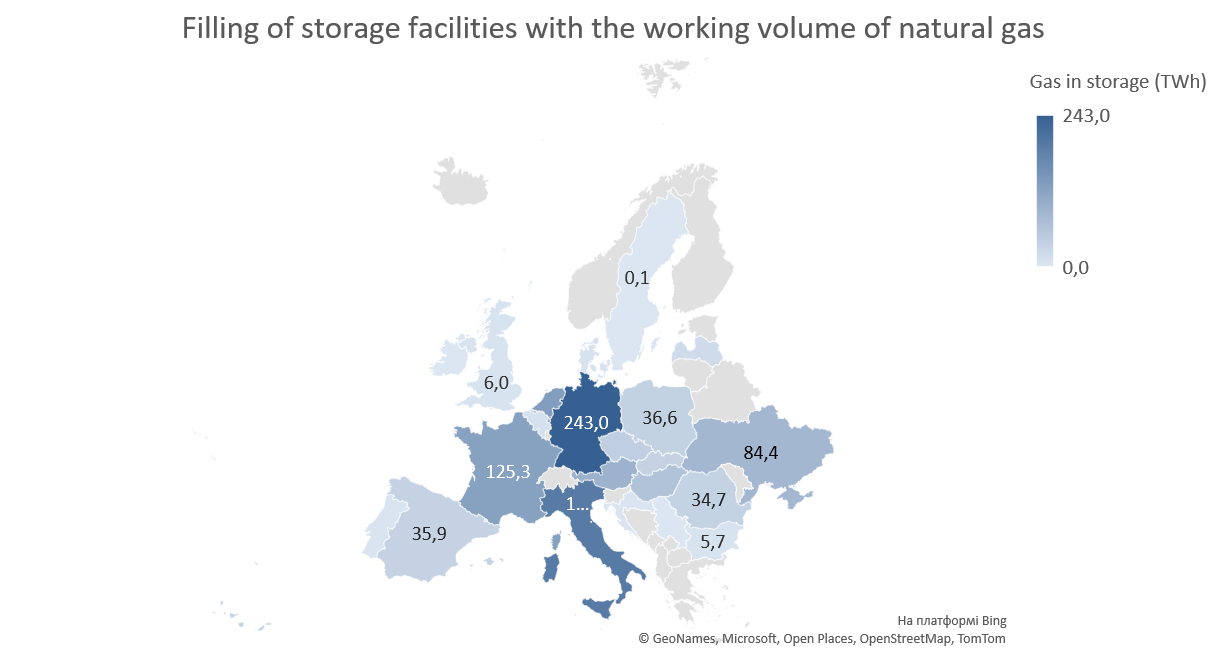
EU storage facilities are 94.74% full, according to the Aggregated Gas Storage Inventory.
The market expects demand to be weaker in October compared to September.
European LNG terminals operated at an average capacity of 75.695%.
As of October 9, LNG stocks in the EU amounted to 4.520 million cubic meters, according to the Aggregated LNG Storage Inventors.
The storage level of the largest LNG exporter, the United States, according to the latest EIA data as of October 4, 2024, was 3.629 billion cubic feet.
Gas supplies through the Westerled pipeline from Norway were suspended and it remained without flows due to the outage, which ended on October 13.
Russian gas exports to Hungary are expected to increase in 2025 after a memorandum of understanding was signed on Thursday to increase flows through the Turkish Stream pipeline, potentially offsetting some of the loss of Russian flows through Ukraine after the supply is cut off in 2025. This may affect the price curve.
On the related oil market, geopolitics remains the main driver of market sentiment. Brent crude oil prices were trading at USD 80.53/barrel on October 11, as Israel considers retaliatory actions against Iran.
Gas balance in Ukraine
Last week, natural gas imports from Hungary, Slovakia and Moldova averaged 11.4 mcm per day, while exports from the customs warehouse amounted to 1.1 mcm to Poland and Slovakia. Ukraine had about 12.6 billion cubic meters in storage facilities. Injections amounted to approximately 32 million cubic meters per day.
Public procurement
Last week through Thursday, 6 tender procedures were held for the purchase of natural gas by budgetary institutions and state-owned enterprises. In total, 204,637.58 cubic meters of natural gas worth UAH 2,998,365.57 were sold at the largest tenders. The largest contract was awarded to MEK, which will supply 110 thousand cubic meters of natural gas to the Education Department of Skorokhodiv Village Council at an initial price of UAH 14.61 per cubic meter. The average price increased and amounted to UAH 14.70 per cubic meter. Prices ranged from UAH 14.61 to UAH 14.89 per cubic meter.
Interesting of the week
The current cost of using the short haul service for the transportation of natural gas through interstate entry and/or exit points will remain in place through the first quarter of 2025. This will allow the transportation of natural gas imported to Ukraine through the short haul service and stored in Ukraine’s UGS facilities in the customs warehouse mode under current conditions.
The current tariffs for GTSOU services are set for the regulatory period 2020-2024. The GTSOU is consulting with the NEURC to set new tariffs that will maintain the economic attractiveness of the GTS and encourage customers to use its capacities.
Hungary and Russia’s Gazprom have agreed on a possible increase in gas supplies to this EU country. This was stated by Foreign Minister Peter Siyarto during a gas forum in St. Petersburg, Russia, reports Evropeiska Pravda. He emphasized that in 2024 the country will receive a total of 6.7 billion cubic meters of Russian gas. The Hungarian Foreign Minister said that “the most important step in Hungary’s energy security in recent years has been the construction of the Turkish Stream gas pipeline, through which Russian gas goes to European countries via the southern route.”