

Gas price: Ukraine and Europe. Market review January 8 - 12, 2024

Gas price: Ukraine and Europe. Market overview
During the last week, natural gas prices in Ukraine continued their downward trend, similar to the trends of European hubs.
Ukrainian Energy Exchange
Last week, the January, February 2024 resource was traded. In general, positions for the purchase and sale of natural gas were formed by 2 companies: Naftogaz Trading, Kraft Energy.
Starting prices of resources decreased during the week. As a result, as of Friday, the average starting price of the resource in UGS was lower than Monday by 1.04%.
Over the last week, buy positions were sold. A total of 15,500 thousand cubic meters of natural gas were sold. The January resource from GTS and UGS was purchased last week by the Naftogaz Trading Company at the prices of sold positions in the range of UAH 12,100-12,339 excl. VAT.
On the short-term natural gas market of UEEX, participants formed applications in GTS and UGS. The sale of gas took place on the within-day market. In total, 7 agreements with a total volume of 49 thousand cubic meters were concluded. During the week, the short-term market also recorded a price decrease. Marginal prices formed based on the results of the auctions are shown in the graph below.
European market
Last week the market was focused on weather forecasts. Gas prices fell in the first half of last week due to heavy deliveries from Norway, which is currently the most important supplier to the UK and Europe. Forecasts of mild weather sent natural gas prices plummeting, with traders calling the situation a "gas sell-off" after the Christmas holiday.
European gas prices rose on Friday amid worsening forecasts, a power outage at the Aasta Hansteen gas field in Norway, with a production capacity of 25.8 million cubic meters/day, and rising tensions in the Middle East. At the same time, some market participants see that the latter may affect some LNG supplies to the EU.
Prices of contracts with delivery in the relevant term, EUR/MWh, 11.01.2024
| Instrument | THE | CEGH | TTF | TGE/POLPX | CEEGEX/HUDEX | Average price |
|---|---|---|---|---|---|---|
| Day1 | 31,41 | 31,1 | 30,95 | 34,31 | 29,58 | 31,47 |
| M+1 | 31,35 | 30,92 | 30,82 | 35,88 | 30,21 | 31,84 |
| Q+1 | 31,3 | 31,71 | 30,81 | 35,36 | 31,54 | 32,14 |
| S+1 | 31,43 | 31,92 | 30,95 | 44,51 | 31,73 | 34,11 |
Contracts for a month ahead, in all analyzed hubs, had a different trend in relation to spot prices - an increase in price by an average of 1.10%. Quarter-on-quarter prices were higher than spot prices by an average of 2.17%. Prices for the season in advance with an average value of 34.11 EUR/MWh were higher compared to spot prices by an average of 7.94%.
February LNG futures in Asia, the JKM Platts Future index, traded at USD 403 per thousand cubic meters last Thursday. Asia’s largest economy, China, has continued to maintain high levels of imports since December, with gas imports reaching a record high of 12 million tons, while pipeline gas and LNG imports rose 10% year-on-year to 163 billion cubic meters.
Futures for LNG delivered to North-West Europe (LNG North West Europe Marker) traded at the level of 350 USD per thousand cubic meters.
European gas prices rose on Friday, January 12. On the Ice Endex, the base monthly TTF contract traded up EUR 1.01 to EUR 31.83/MWh, and DA - up EUR 0.55 to EUR 31.40/MWh.
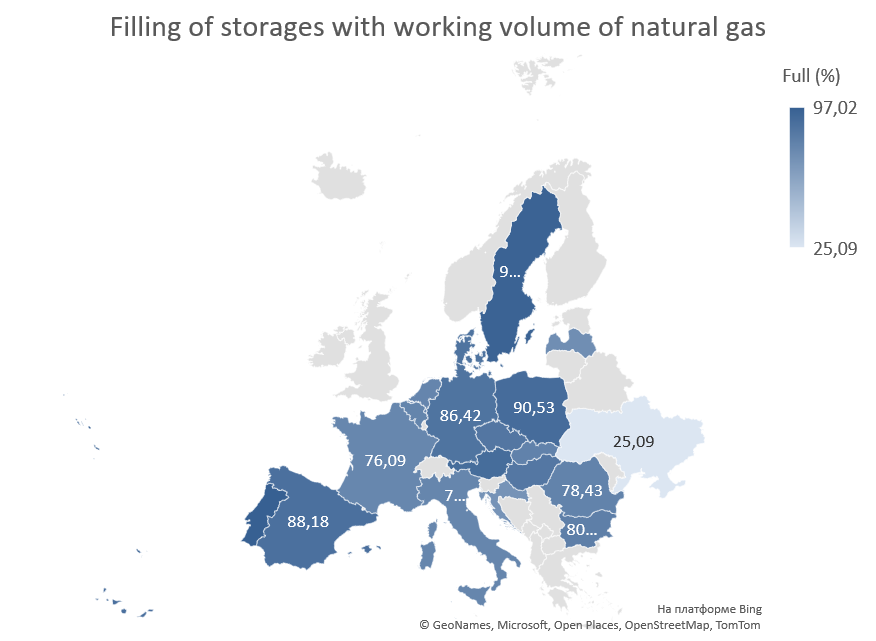
European gas storage was 81.77% full as of January 10, according to the Aggregated Gas Storage Inventory.
Since the beginning of the year, Norwegian pipeline gas flows have been operating at near capacity, but the market will be watching the latest production forecast from Norway’s state administration. An unplanned gas shutdown at the Aasta Hansteen gas field in Norway led to a reduction in gas flows by 8 million cubic meters per day on Friday, TSO Gassco said. Nominated gas sales from Norway to Europe last came in at 343.6 million cubic meters per day, compared with 351 million cubic meters per day on Thursday.
European LNG terminals operated with an average capacity of 70.01%.
According to the latest EIA data on January 5, 2024, the storage filling level of the largest LNG exporter, the USA, was 3.336 billion cubic meters. ft. and was 11.6% above the 5-year average.
As for oil, the two-channel crisis has increased the attention of oil markets to the reliability of supply. Disruptions in oil production in Libya have further exacerbated supply problems.
Oil prices rose 2% on Friday, January 12, to trade at USD 79.29 a barrel after the US and UK launched airstrikes against Houthi rebels in response to attacks on commercial vessels in the Red Sea.
Gas balance in Ukraine
Imports of natural gas last week were almost non-existent. Export flows from the "customs warehouse" to neighboring countries were observed. Exports increased compared to previous periods and remained at an average level of 15.5 million cubic meters per day last week. About 12.2 billion cubic meters were in Ukraine’s storage facilities, the daily selection increased to 100 million cubic meters per day - in connection with the cooling and the growth of exports from the "customs warehouse".
Public procurement
Last week, 16 tender procedures for the purchase of natural gas by budget institutions and state enterprises were held. In total, 1.06 million cubic meters of natural gas of the largest tenders (top-10) were sold in the amount of UAH 13.90 million. The largest contract was received by "TEPLA ENERGETYCHNA KOMPANIYA" LLC, which will supply 178,000 cubic meters to the Myrhorod sanatorium "Slava" at an initial price of UAH 13.79 excluding VAT. The prices of large tenders fluctuated in the range of UAH 12.78-13.79 excl. VAT. In addition, Ukrtransgaz held a tender for the purchase of 1.7 million cubic meters of natural gas, the winner is awaiting a decision, the procedure for eliminating inconsistencies and justifying the low price is ongoing.
Interesting for the week
According to preliminary data from the Kpler company, last year European countries, excluding Turkey, imported slightly more than 20 billion cubic meters of LNG from Russia, which is 1% less than in 2022. Of the total, Spain became the largest importer: supply increased by more than a third to 6.7 billion cubic meters and Belgium also increased imports by 41% to 6.6 billion cubic meters. In France, the third largest importer, supply decreased by 35% compared to the previous year to 4.7 billion cubic meters. The previous EU agreement, which gives EU countries the legal authority to block the import of Russian gas, has not yet become binding. And even the implementation of the embargo will only affect the booking of new regasification capacities at the terminals, while the "majority" of these places are currently already reserved under long-term contracts.
Consultancy firm Icis has predicted that Europe is likely to see an increase in gas demand this year, but energy consumption will remain below the level seen before the current energy crisis in 2017-2021 Gas demand is set to grow slowly by 8%, or 273 TWh, on an annualized basis, but will still be 12% below the five-year average. Much of this additional demand will be met by even more LNG, according to the Energy Prospects 2024 report, which will be published later this month.


