

Gas price: Ukraine and Europe. Market overview November 25 - 29, 2024

Gas price: Ukraine and Europe. Market overview
Over the last week, natural gas prices in Ukraine have been rising, in contrast to the trends in European hubs.
Ukrainian Energy Exchange
Last week, trading continued in November, December 2024, and January 2025. In total, 15 companies formed positions for the purchase and sale of natural gas: Elektro-Gaz, Energigaztrade, GTS Operator of Ukraine, Naftogaz Trading, Energo Zbut Trans, National Resources of Ukraine, Kyivvodokanal, Ukrnaftoburinnya, Poltavagaz, IGC, Nadra-Geoinvest, and Ukrnafta.
The starting prices of resources were growing throughout the week. As a result, as of Friday, the average starting price of December resources in the GTS was 4.56% higher than on Monday.
Activity increased significantly last week. Both sell and buy positions were sold. In total, 213030 thousand cubic meters of natural gas were sold. Of these, 194 million cubic meters were purchased by PPC Naftogaz-Trading, Ukrnaftoburinnya sold 9 million cubic meters, and Ukrnafta sold 5.6 million cubic meters.
On the short-term natural gas market of the UEEX, participants formed bids in the GTS and UGS. Prices increased during the week. On Friday, November 29, the weighted average price of the SSP amounted to UAH 15,250 excluding VAT.
European market
Last week, the market was “surprised” by the drop in natural gas prices despite significant withdrawals from European storage facilities and ongoing risks associated with Russian gas flows. It was reported that Gazprom plans to publish its forecast for 2025, which excludes any agreement on gas transit to Ukraine, confirming that there will be no extension of the agreement in the new year. Supply to Europe has also been hampered by US sanctions against Gazprombank, which processes payments for European customers. According to the sanctions, all such transactions must be completed by December 20.
Overall, gas prices have softened, partly due to the resumption of Freeport LNG operations in the US, which has eased concerns about supply shortages.
Prices of contracts with delivery within the relevant period, EUR/MWh, 11/28/2024
| Іnstrument | THE | CEGH | TTF | TGE/POLPX | CEEGEX/HUDEX | Average price |
|---|---|---|---|---|---|---|
| Day1 | 47,07 | 47,07 | 46,46 | 48,16 | 46,31 | 47,01 |
| M+1 | 47,19 | 47,02 | 46,27 | 47,55 | 47,39 | 47,08 |
| Q +1 | 47,51 | 47,53 | 46,63 | 46,77 | 47,61 | 47,21 |
| S +1 | 45,76 | 46,45 | 44,8 | 43,21 | 45,95 | 45,23 |
Month-ahead contracts at all the analyzed hubs showed a different trend in relation to spot prices, with an average increase of 0.16%. Prices a quarter ahead were 0.44% higher than spot prices on average. Season-ahead prices with an average value of EUR 45.23/MWh tended to decline by an average of 3.75% compared to spot prices after the ceasefire agreement between Israel and Hezbollah.
British short-term gas prices fell last Thursday, with the spot price trading at 115.35 p/therm, driven by strong supply that weakened the balance of the UK market. The decline in domestic demand was offset by higher demand for gas for power generation, while stable supply and significant LNG supplies suggest a slightly weaker market next week. Similarly, forward gas prices were bearish, reflecting a subdued fundamental outlook and the NBP Summer-25 contract closed 1% lower at 109 p/therm.
Geopolitical tensions are pushing up LNG prices in Europe, but major buyers remain cautious.
The onset of cold weather in South Korea and Japan affected the Asian spot LNG market last week, after prices rose above USD 15 per thousand cubic meters. Although major buyers such as China and India remain cautious due to high spot prices, the harshness of winter will be a key factor affecting trade activity. The January futures for LNG in Asia, the JKM Platts Future index, settled on November 27 at USD 537.72. US dollars per thousand cubic meters.
The LNG North West Europe Marker closed last Wednesday at USD 517.13 per thousand cubic meters.
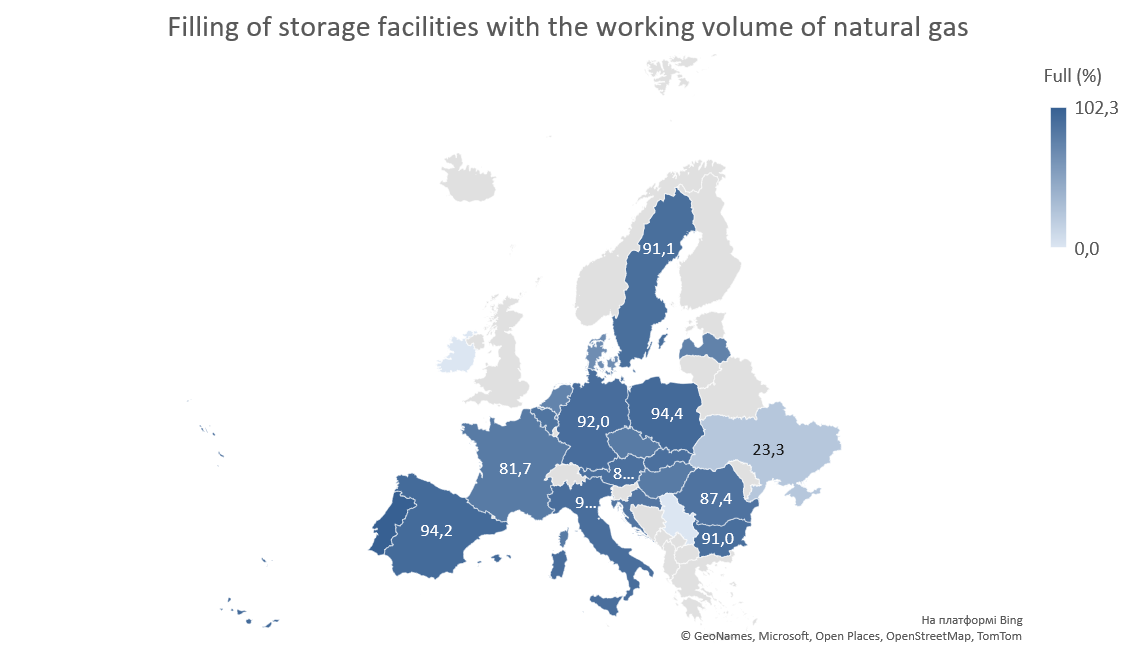
Storage facilities in the EU are 86.65% full, according to the Aggregated Gas Storage Inventory as of November 27.
European LNG terminals operated at an average capacity of 77.45%.
As of November 27, LNG stocks in the EU amounted to 3.998 million cubic meters, according to the Aggregated LNG Storage Inventors.
According to the latest EIA data, the storage level of the largest LNG exporter, the United States, as of November 22, 2024, was 3.967 billion cubic feet.
As for pipeline Russian gas, according to Eustream, bids for flows to Austria from Slovakia were on par with the volumes seen over the past three days. Applications to the Czech Republic from Slovakia increased, but were in line with the levels seen this month. Russia cut off supplies to Vienna-based energy company OMV over a contract dispute in mid-November, but overall gas exports to Austria remained stable as other companies increased their purchases.
Norwegian gas will remain competitive in Europe with the lowest production costs.
On related oil markets, the price of Brent crude oil settled at USD 72.77 per barrel on November 21. Oil prices reflect growing concerns about risk and uncertainty, especially in connection with the ongoing war in Ukraine.
Gas balance in Ukraine
No natural gas was imported last week, while exports from the customs warehouse amounted to 9 mcm to Poland, Slovakia and Moldova. Ukraine had about 11.7 billion cubic meters in storage facilities. Withdrawals amounted to about 56 million cubic meters per day.
Public procurement
Last week, four tender procedures were held for the purchase of natural gas by budgetary institutions. In total, 564,748.40 cubic meters of natural gas worth UAH 8,263,304.93 were sold at the largest tenders. The largest contract was awarded to MEK, which will supply 510,000.00 cubic meters of natural gas to the Education Department of Sokyryany City Council at an initial price of UAH 14.64 per cubic meter. The average price increased and amounted to UAH 14.65 per cubic meter. Prices ranged from UAH 14.53 to 14.72 per cubic meter, excluding VAT.
Interesting for the week
The Austrian oil and gas company OMV has confiscated 230 million euros worth of natural gas supplied by Gazprom in October, enforcing an international arbitration award. According to Ukrinform, this was reported by Reuters with reference to knowledgeable interlocutors. “According to three sources close to Gazprom and OMV, the Austrian company has confiscated gas supplies worth 230 million euros in October. According to one source close to the Russian company, this was the first time that a customer from the European Union did not pay for gas supplies from Gazprom,” the article says.
The EU Court of Justice dismisses Russia’s lawsuit over violation of EU rules on the Nord Stream 2 pipeline division. The court found that Nord Stream 2 (NS2) could have foreseen that it would not meet EU criteria when it built the pipeline, which was completed in 2021. The NS2 pipelines have never exported gas, and one of its pipes, along with the existing Nord Stream 1 (NS1) pipelines, was blown up in September 2012. The pipelines were built to pump 110 billion cubic meters (bcm) of natural gas per year across the Baltic Sea to Germany, but never reached that level. NS1 pumped over 59 bcm in 2021.
“The court explains that Nord Stream 2 AG made and continued to invest in its pipeline at a time when it had no assurance that EU law would continue to apply to its pipeline,” the statement said.


