Gas price: Ukraine and Europe. Market overview May 4 - 8, 2026
In the "Medium and Long-Term Market" section of the UEEX, trading in the resource continued in May and June 2026. In total, positions for the sale or purchase of natural gas were formed by 8 companies: MC Ukrnaftoburinnia, GTS Operator of Ukraine, Ukrtransinvest, etc. During the week, 2,600 thousand cubic meters of natural gas were sold in the section. The positions of the GTS Operator of Ukraine were successful. In addition, heat generating enterprises, namely: Cherkasyteplokomunenergo and Concern "Municipal Heat Networks", for the first time purchased natural gas on the exchange for electricity generation. Sales prices were in the range of 22050-22700 UAH/thousand cubic meters excluding VAT with a downward trend.
On the short-term natural gas market of the UEEX, participants formed orders on the within-day market and the day-ahead market. In total, 39 deals were concluded with a total volume of 2,227 thousand cubic meters.
European gas prices were hit by mixed news from the Middle East last week, with M+1 gas contracts in some markets experiencing significant volatility, hitting 3-week highs and 2-week lows on consecutive days. Geopolitical turmoil, uncertainty over winter supplies and rising structural demand mean that circumstances can change quickly.
Gas prices fell significantly for most 2026 contracts on Thursday, amid news of a possible deal between the US and Iran to end the conflict and ensure free movement of maritime traffic through the Strait of Hormuz: after the successful passage of the Liberian-flagged LNG tanker Mubaraz, other loaded LNG tankers appear to have passed through the strait.
DA gas prices continued this trend on Friday morning. This decline is in line with sentiment regarding comments from various news outlets confirming Iran’s willingness to negotiate over its nuclear program, which is the main cause of disagreement between the parties, increasing the likelihood of an end to the conflict. This urgent news was partially offset by reduced flows from Oseberg in Norway two days before the scheduled start of the maintenance period, which tightened the gas system on May 9.
Short-term prices have shown that they can react quickly to weather conditions and systemic imbalances. Even outside peak winter periods, volatility remains a feature of the market. A colder May forecast stimulates additional demand, while wind power generation in Europe is operating below average. Declining renewable energy generation is straining the power grid and forcing greater reliance on gas-fired power plants.
Hedge funds have increased their net long positions in the European gas market, according to the latest traders’ commitment report. With little change in short positions, the funds added another 26 TWh of long positions, bringing the total net long position to 288 TWh.
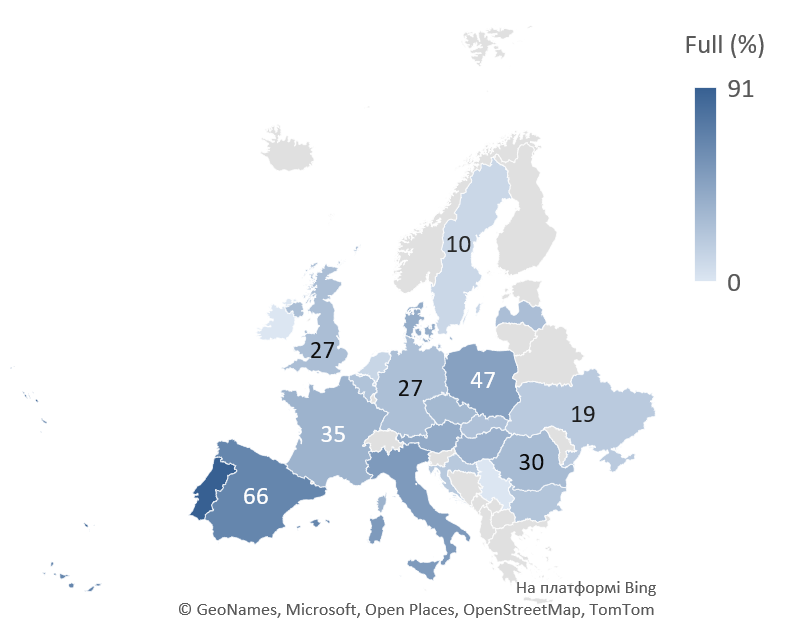
EU gas storage capacity is at 34%, but gas injections are proceeding at a rapid pace of around 10% per month. This has calmed the market in the short term and helped to support prices, despite broader risks.
Natural gas imports from Europe were at 0.11 (+0.3) million cubic meters per day. Imports were present from Poland and Hungary. Exports from customs warehouses were absent. Ukraine’s storage facilities contained 10.33 (+1.48%) billion cubic meters of natural gas. There was no withdrawal from underground storage facilities, but there was injection - about 31 million cubic meters per day.