

Gas price: Ukraine and Europe. Market overview May 27 - 31, 2024

Gas price: Ukraine and Europe. Market overview
Over the last week, natural gas prices in Ukraine have been subject to diverse fluctuations, staying in a narrow price range.
Ukrainian Energy Exchange
Last week, trading in May and June 2024 continued. In general, 4 companies formed positions for the purchase and sale of natural gas: Ukrnafta, GTS Operator of Ukraine, PPC Oil and Gas Trading, and Kyivvodokanal.
The starting prices of resources had a diverse dynamics. As a result, as of Friday, the average starting price of June resources in the GTS was 0.23% higher than on Monday.
Last week, both sell and buy positions were sold. In total, 41420 thousand cubic meters of natural gas were sold. Of these, Ukrnafta sold 35,600 thousand cubic meters and the Ukrainian GTS Operator purchased 5,600 thousand cubic meters of natural gas. The quotation prices formed as a result of the trades are shown in the chart.
On the short-term natural gas market of the UEEX, participants formed bids in the GTS and UGS. Gas was sold on the within-day market. The marginal prices resulting from the auction are shown in the chart below.
European market
Last week, continental gas markets rose by several percent as the upward trend of the previous week continued, while the UK NBP market remained closed on Monday due to a national holiday. However, during Tuesday’s session, TTF was down 5%, indicating that volatility remains after the potential impact of Gazprom’s cutbacks in flows to Austria’s OMV.
Spot prices for UK NBP also rose due to rising demand and supply uncertainty over the prolonged planned outages in Norway, reaching 83.50 p/therm on Thursday, May 30, while the price of Win-24 gas rose by 2% last Thursday to settle at 103.61 p/therm, driven by growing concerns over a possible premature halt to Russian exports through Ukraine.
On Friday, the benchmark TTF M+1 traded higher by EUR 0.11 to EUR 35.30/MWh amid continued “uncertainty” and fears of further escalation over Russia’s war in Ukraine.
This week, maintenance is scheduled to be suspended in Norway at various facilities, and the market should see an increase in flows to the continent and the UK, which may limit some upside potential.
Prices of contracts with delivery in the respective period, EUR/MWh, 05/30/2024
| Instrument | THE | CEGH | TTF | TGE/POLPX | CEEGEX/HUDEX | Average price |
|---|---|---|---|---|---|---|
| Day1 | 34,99 | 36,47 | 35,05 | 33,42 | 32,52 | 34,49 |
| M+1 | 34,93 | 36,42 | 35,07 | 35,42 | 35,46 | |
| Q +1 | 35,79 | 37,24 | 35,77 | 36,26 | 36,27 | |
| S +1 | 40,7 | 41,42 | 40,13 | 40,83 | 40,77 |
Month-ahead contracts at all the analyzed hubs had the same trend in terms of spot prices, with an average increase of 2.17%. Prices a quarter ahead were 4.49% higher than spot prices on average. The season-ahead prices with an average value of EUR 40.77/MWh tended to increase by an average of 17.48% compared to the spot prices.
The season-ahead prices with an average value of EUR 40.77/MWh tended to increase by an average of 17.48% compared to the spot prices. The July futures for LNG in Asia, the JKM Platts Future Index, closed on May 30 at USD 428 per thousand cubic meters. The LNG North West Europe Marker futures for LNG delivered to Northwest Europe amounted to USD 381 per thousand cubic meters. Average demand was lower due to the partial holiday and relatively low market liquidity due to the Corpus Christi holiday celebrated in Germany and some parts of Europe.
The average temperature in Europe’s largest gas consumer, Germany, is expected to rise by 0.6C to an average of 16.2C this week, only 0.1C below the seasonal norm, while in neighboring France the average temperature will be 17.4C, 0.1C above the norm.
The occupancy rate of pan-European gas storage facilities stood at 69.48% as of May 29, according to the latest Aggregated Gas Storage Inventory data, up 1.8% week-on-week and 0.5% year-on-year.
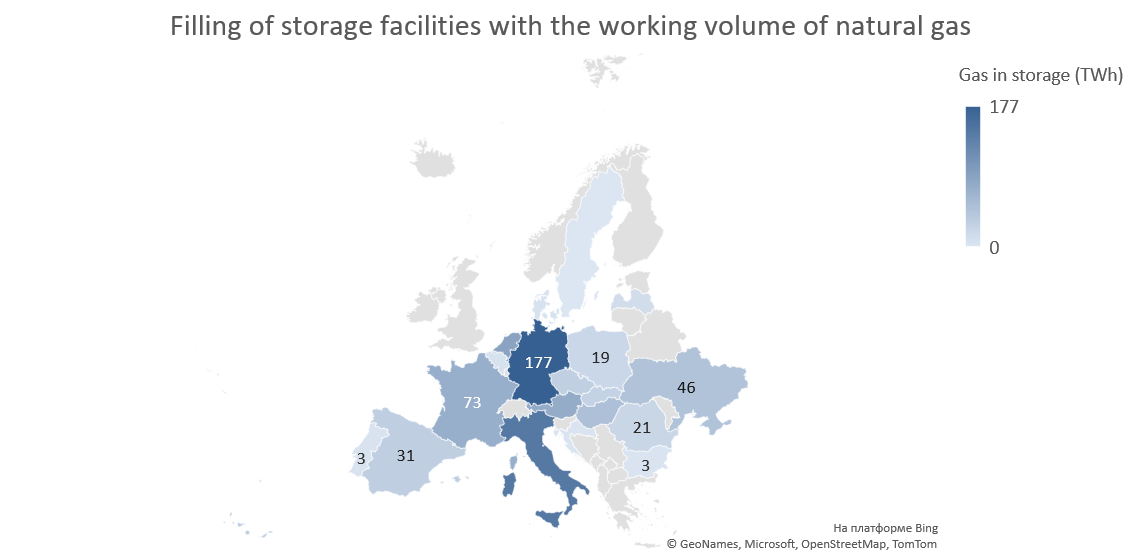
European LNG terminals operated at an average capacity of 70.73%, with low levels of receipts across the continent. There are various disruptions at European terminals, and the Belgian Zeebrugge terminal stopped for two days. 19 cargoes are scheduled to arrive in Northwest Europe during June, which is significantly less than the 97 cargoes that arrived in June 2023. LNG supply also remains a problem in the UK, as only one cargo is expected to arrive in the country in the coming weeks.
As of May 29, LNG stocks in the EU amounted to 4.561 million cubic meters, according to the Aggregated LNG Storage Inventors.
The storage level of the largest LNG exporter, the United States, according to the latest EIA data as of May 24, 2024, was 2.795 billion cubic feet.
Pipeline gas supplies remained relatively stable last week and the first tranche of maintenance outages in Norway is due to end this Tuesday. Norwegian flows to Europe were observed at 303.9 million cubic meters per day on May 31, compared to 286.6 million cubic meters per day the Friday before last, TSO Gassco data showed.
On the related market, Brent crude traded at USD 81.86 per barrel on May 31 as economic activity in the US showed that borrowing costs are likely to remain higher for longer, potentially reducing fuel demand. News from US policymakers that interest rates are likely to remain “higher for longer” continues to put pressure on prices. In addition, OPEC+ is going to discuss extending production cuts.
Gas balance in Ukraine
Last week, natural gas imports were present only from Hungary, averaging 1.08 million cubic meters per day. Exports to Poland and Slovakia averaged 2.75 million cubic meters per day. Exports increased compared to previous periods. Ukraine had about 9.2 billion cubic meters in storage. Injections amounted to approximately 25 million cubic meters per day.
Interesting for the week
In July 2024, a new phase of the Vertical Corridor initiative will start. GTS operators of Central, Southern and Eastern Europe presented the next stage of the Vertical Corridor initiative - a binding stage for the distribution of new (increased) capacity between the participating countries’ GTSs. The meeting was organized by the Greek operator DESFA. The binding stage of the distribution of new (increased) capacity at the relevant interconnection points of the gas transmission systems (GTS) will start in July 2024. The representatives of the participating companies, including DESFA and Gastrade (Greece), ICGB and BULGARTRANSGAZ (Bulgaria), TRANSGAZ (Romania), FGSZ (Hungary), EUSTREAM (Slovakia), VMTG (Moldova) and OGTSU (Ukraine), confirmed their readiness to simultaneously fulfill this commitment, in accordance with the EU NC CAM Regulation adopted by the European Commission.
The State Service of Geology and Subsoil is preparing seven oil and gas lots for auction. Six sites are located in the western oil and gas region and one in the eastern region. Applications were also filed to announce a tender for production sharing agreements for two new subsoil blocks. Conversion of 17 existing special permits into production sharing agreements was initiated.


