Gas price: Ukraine and Europe. Market overview May 11 - 15, 2026
In the section "Medium and Long-term Market" of the UEEX, trading in the resource continued for May and June 2026. In total, positions for the sale or purchase of natural gas were formed by 9 companies: MC Ukrnaftoburinnia, GTS Operator of Ukraine, GPK Naftogaz Trading, etc. During the week, 3,870 thousand cubic meters of natural gas were sold in the section. The positions of the GTS Operator of Ukraine, Cherkasyteplokomunenergo and GSC Naftogaz Trading were successful - for the purchase of gas with delivery in May and June. In conditions of decreasing prices, companies are actively purchasing gas, including for electricity generation. Sales prices were in the range of 21012-22050 UAH/thousand cubic meters excluding VAT with a downward trend.
On the short-term natural gas market of the UEEX, participants formed orders on the intraday market and the day-ahead market. In total, 72 deals were concluded with a total volume of 3,187 thousand cubic meters.
European gas prices have been mixed over the past week, with demand expected to ease in the coming days as warmer weather is forecast.
The optimism sparked by the statement of the Iranian Islamic Revolutionary Guard Corps, in which it announced that “after neutralizing the aggressor’s threats and implementing new protocols, a safe and stable passage through the Strait of Hormuz will be ensured,” has faded. As of today, there is no timetable for another round of peace talks between the United States and Iran, as the United States apparently prefers to use economic pressure to extract concessions from Iran. At present, neither side seems willing to back down from its existing demands. Industry sources suggest that both Iraq and Pakistan have reached agreements with Tehran to secure LNG flows. Two tankers carrying Qatari LNG – the Al Kharaitiyat and the Mihzem – have already passed through the strait to Pakistan.
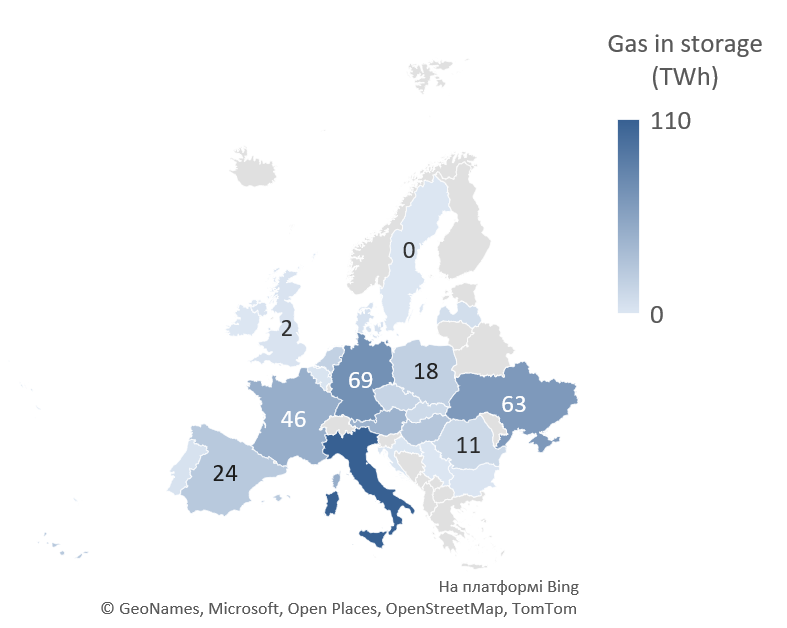
Europe is seeing an increase in gas storage capacity, although European gas futures markets still lack the market structure needed to drive capacity. European gas storage remains at a four-year low, with the capacity level across Europe now at 35.85%, and daily injection activity remains limited. While injection rates have recently improved, the market remains vulnerable ahead of summer.
So for traders, the concern is no longer focused on a single event. Gas markets are now reacting to a combination of prolonged LNG supply disruptions, tight storage conditions and increasing global competition for gas supplies.
Natural gas imports from Europe were at 0.11 million cubic meters per day, unchanged from the previous week. Imports were present from Poland and Hungary. Exports from customs warehouses were absent. Ukraine’s storage facilities contained 10.55 (+2.13%) billion cubic meters of natural gas. There was no withdrawal from underground storage facilities, but there was injection - about 31 million cubic meters per day.