Gas price: Ukraine and Europe. Market overview March 30 – April 3, 2026
In the "Medium and Long-Term Market" section of the UEEX, trading in the resource continued in April and May 2026. In total, positions for the sale or purchase of natural gas were formed by 5 companies: MC Ukrnaftoburinnia, GTS Operator of Ukraine, Ukrzaliznytsia, Energy Business, LTK Electrum. During the week, 1 million cubic meters of natural gas were sold in the section. Natural gas was sold with delivery in April. The GTS Operator of Ukraine’s purchase positions were successful. Sales prices were in the range of 24,650-24,700 UAH/thousand cubic meters excluding VAT with a tendency to increase.
On the short-term natural gas market of the UEEX, participants formed orders on the within-day market and the day-ahead market. In total, 32 deals were concluded with a total volume of 1,639 thousand cubic meters.
Global energy markets are driven by rising geopolitical risks and widespread LNG supply disruptions, leading to high risk premiums in gas contracts. The ongoing conflict with Iran, combined with disruptions in key exporting regions, has led to a reduction in global supplies at a critical time early in the Sum-26 period, making markets vulnerable to further growing shocks.
U.S. LNG exports hit a record high in March as plants exceeded capacity and new plants were commissioned, preliminary data from LSEG showed.
Short-term gas markets saw prices fall in the first half of the week. The decline was driven by renewed optimism about a potential ceasefire between the U.S. and Iran. However, markets reversed course on Wednesday morning, with M+1 and June-26 contracts trading higher. This shift came after President Trump’s speech, which did not outline a clear path to de-escalation of the conflict with Iran. The US President has said he will "return Iran to the Stone Age", prompting markets to reassess the risk of further military escalation. The lack of any update on the reopening of the Strait of Hormuz has added to uncertainty, supporting current prices.
Israel’s Energy Ministry announced on Thursday that Israel’s Leviathan gas field, one of the largest in the Eastern Mediterranean, will resume production after a month-long shutdown due to the war. The field, operated by Chevron, has been idle since the US-Israeli attacks on Iran on February 28. Natural gas supplies to the domestic market will continue and will be supplemented by the integration of an additional platform into the production system.
According to the CEO and Minister of Energy of QatarEnergy, it may be necessary to apply for force majeure in relation to long-term LNG supply contracts in Italy, Belgium, South Korea and China for a period of up to five years.
By the end of the week, most markets had moved into the Easter weekend.
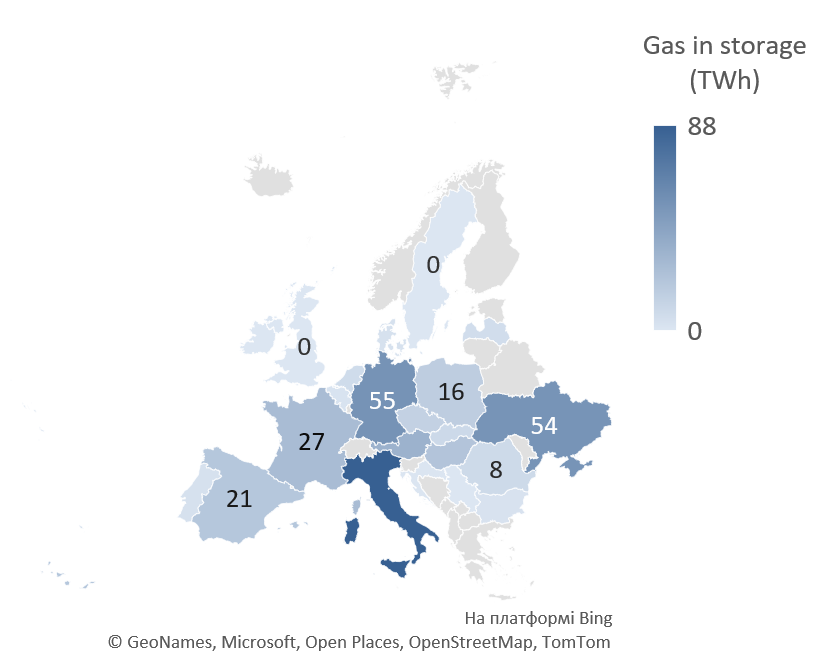
Current gas storage capacity in Europe is 27.92% of total capacity, according to AGSI. Forward curves are increasingly influenced by geopolitical events rather than seasonal fundamentals.
Natural gas imports from Europe in April fell to 0.8 million cubic meters per day (-96.75%). Inflows decreased against the background of rising quotations in Europe. Imports were present from all neighboring European countries until March 31, and from April 1 – only from Poland. Exports from the bonded warehouse were present to Poland in the volume of 0.2-0.6 million cubic meters per day. Ukraine’s storage facilities contained 9.54 (+1.89%) billion cubic meters of natural gas. There was practically no withdrawal from underground storage facilities, but small volumes of injection were observed - about 22 million cubic meters per day.