

Gas price: Ukraine and Europe. Market overview March 11 - 15, 2024

Gas price: Ukraine and Europe. Market overview
Over the last week, natural gas prices in Ukraine have been subject to diverse fluctuations, generally maintaining a downward trend.
Ukrainian Energy Exchange
Last week, trading in the March 2024 and April 2024 contracts continued. In total, 7 companies formed positions for the purchase and sale of natural gas: NEP, Stalkanat, RP-Group, GTS Operator of Ukraine, Ukrnafta, Naftogaz Trading, and Kraft Energy.
Starting prices of resources decreased throughout the week. As a result, as of Friday, the average starting price of resources in UGS facilities was 0.39% lower than on Monday.
Last week, the Naftogaz sold its purchase positions. In total, 33600 thousand cubic meters of natural gas were sold. The largest volumes - 19000 thousand cubic meters - were purchased by the GTS Operator of Ukraine - March and April resources in the GTS.
On the short-term natural gas market of the UEEX, participants placed bids in the GTS and UGS facilities. Gas was sold on the intraday market in UGS facilities, where 22 thousand cubic meters were sold.
European market
Supply continues to dominate demand on European gas markets, with LNG imports and gas reserves remaining above historical levels. Some of the temporary upside factors seen the week before last - geopolitical risk, weak wind generation, and the switch from coal to gas - have now disappeared as the broader picture of LNG supply prevails.
On Thursday, the main European gas and energy hubs saw significant gains as prices moved upward, triggered by reports from Japan of a 5.8-magnitude earthquake in the Fukushima region. News from Japan has raised concerns about the possible closure of nuclear power plants in the Fukushima region and across Japan. The recent resumption of nuclear power plants in Japan has led to a decrease in demand for gas for electricity generation. Any shutdown of operating nuclear reactors in Japan could lead to an increase in LNG demand as gas-fired power plants compensate for the loss of nuclear capacity. The market also received information from the United States, where prices rose due to higher-than-expected withdrawals from storage facilities. This was due to the fact that large US utilities withdrew gas from storage facilities in preparation for the forecasted cold weather.
Prices of contracts with delivery within the relevant period, EUR/MWh, 03/14/2024
| Instrument | THE | CEGH | TTF | TGE/POLPX | CEEGEX/HUDEX | Average price |
|---|---|---|---|---|---|---|
| Day1 | 25,77 | 27,38 | 25,37 | 27,46 | 22,84 | 25,76 |
| M+1 | 26,36 | 27,46 | 26,1 | 28,81 | 26,6 | 27,07 |
| Q+1 | 26,38 | 27,5 | 26,22 | 28,98 | 26,57 | 27,13 |
| S+1 | 26,51 | 27,65 | 26,4 | 28,81 | 26,78 | 27,23 |
Month-ahead contracts at all the analyzed hubs showed the same trend in terms of spot prices, with an average increase of 5.37%. Quarter-ahead prices were higher than spot prices by an average of 5.61%. The seasonal forward prices with an average value of EUR 27.23/MWh tended to increase compared to the spot prices by an average of 6.02%.
The benchmark monthly contract on the Dutch hub TTF rose to EUR 26.69/MWh in Friday’s trading according to Ice Endex amid increased interest in fuel from Asia due to cold weather and a strengthening carbon market and some supply reduction due to a combination of the ongoing outage at the US LNG export terminal Freeport.
The April futures for LNG in Asia, the JKM Platts Future Index, traded last Thursday, March 14, at USD 304 per thousand cubic meters. The LNG North West Europe Marker was trading at USD 270 per thousand cubic meters.
It is estimated that industrial gas demand in Europe grew by 12% year-on-year in January and by about 6% in February. Further, industrial demand should increase by 5.5 bcm as the EU economy recovers in the second half of the year, while domestic demand for gas should increase by 12 bcm under normal weather conditions.
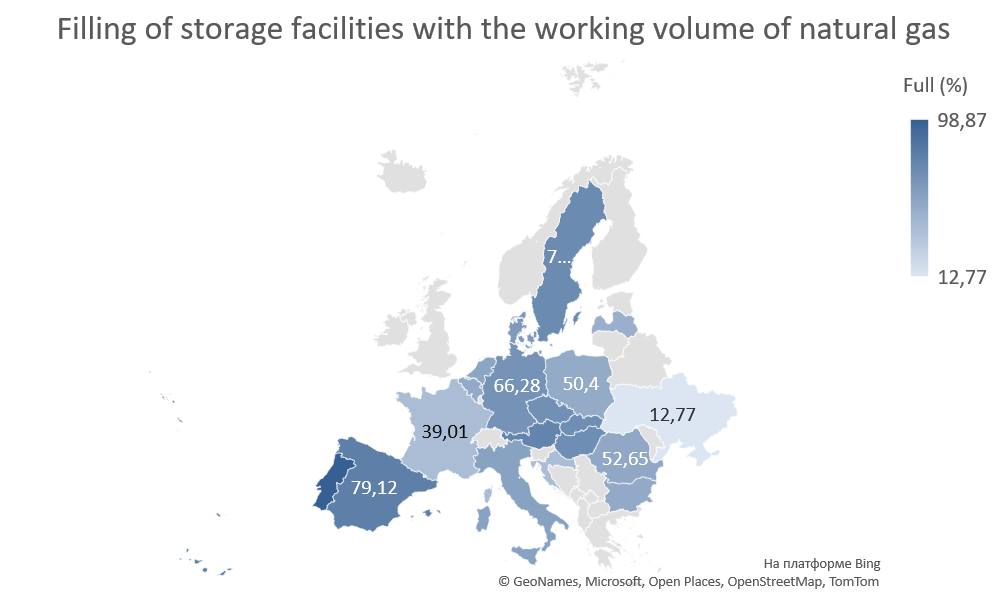
The level of gas storage in the EU fell to 59.9% (686 TWh), according to the latest Aggregated Gas Storage Inventory data as of March 13, compared to the five-year average of 42.7% for this time of year.
As of March 13, LNG stocks in the EU amounted to 3.987 million cubic meters, according to the Aggregated LNG Storage Inventors. Market experts noted the dependence on global LNG markets, which means that there is a sudden dependence on China’s economic development and gas demand in China, which the European market has not seen in the past.
European LNG terminals operated at an average capacity of 69.81%.
The storage level of the largest LNG exporter, the United States, according to the latest EIA data as of March 8, 2024, was 2.325 billion cubic feet. US LNG exports in March totaled 2.8 million tons as of March 11, up 2.12 million tons week-on-week. Of the total volume, 29% was delivered to Europe and about 16% to Asia.
Last week, attacks in the Red Sea continued in the oil industry, resulting in the first casualties of the conflict and further market disruption. The crisis has been supporting oil prices since February. The International Energy Agency’s upward revision of its oil demand forecast for 2024, coupled with declining US inventories and an expected spring increase in Chinese oil demand last week, added momentum to the upward trend. On March 15, Brent crude oil was trading at USD 84.81 per barrel.
Gas balance in Ukraine
Last week, natural gas imports were available from Hungary, at an average daily level of 1.43 million cubic meters. Export flows from the "customs warehouse" to neighboring countries were observed. Exports increased compared to previous periods, remaining at an average level of 3.53 mcm per day. Ukraine’s storage facilities contained about 8 bcm, with daily withdrawals of 45 mcm per day due to the warm weather.
Public procurement
Last week, 7 tender procedures were held for the purchase of natural gas by budgetary institutions and state-owned enterprises. In total, 819.90 thousand cubic meters of natural gas worth UAH 9.14 million were sold at the largest tenders (top 10). The largest contract was awarded to U-GAZ LLC, which will supply 350.00 thousand cubic meters of natural gas to Vadym Hetman Kyiv National Economic University at an initial price of UAH 11.30 per cubic meter. The average price increased and amounted to UAH 11.34 per cubic meter. Prices ranged from UAH 10.88 to UAH 12.09 per cubic meter.
Interesting for the week
Last Tuesday, the European Commission announced the fifth short-term joint tender for gas purchases through AggregateEU, covering gas purchases from May 2024 to March 2025. Participants will have until March 18 to apply, and the matching process will last until March 27.
Foreign customers continue to transport natural gas to Ukraine. In January-February 2024, Ukraine received more than 60 million cubic meters of gas, mostly in short-haul mode. In January-February 2024, Ukraine received more than 60 million cubic meters of gas, mostly in short-haul mode. Also, according to auction platforms, the capacities of neighboring countries’ GTS operators are still being actively booked by traders to transport gas to Ukraine. Dmytro Lypa, CEO of the Ukrainian GTS Operator, noted that the transportation of foreign gas to Ukraine is a positive assessment of the company’s performance.


