

Gas price: Ukraine and Europe. Market overview July 29 – August 2, 2024

Gas price: Ukraine and Europe. Market overview
Last week, natural gas prices in Ukraine remained stable, unlike those of European hubs.
Ukrainian Energy Exchange
Last week, trading in August and September 2024 continued. In total, 4 companies formed positions for the purchase and sale of natural gas: GTS Operator of Ukraine, Ukrnafta, Naftogaz Trading, and Kyivvodokanal.
The starting prices of resources had a diverse dynamic, with slight fluctuations.
Last week, both sell and buy positions were sold. In total, 20420 thousand cubic meters of natural gas were sold. The quotation prices formed as a result of the auction are shown in the chart below.
On the short-term natural gas market of the UEEX, participants placed bids in the GTS and UGS facilities. Gas was sold on the within-day market. A total of 9 agreements were concluded with a total volume of 299 thousand cubic meters. No significant price fluctuations were recorded on the short-term market during the week.
Margin prices formed as a result of trading are shown in the chart below.
European market
Last week, increased tensions in the Middle East had a negative impact on the market and led to higher gas prices. Israel may suspend production at its Tamar and Leviathan gas fields in the event of an escalation of the war, and there may be interruptions in Israeli gas supplies to Egypt, which could lead to further increases in the price of LNG.
Higher and in some places abnormally high temperatures and reduced wind power generation increased demand for power generation and also contributed to higher prices at the end of the week. Further problems at the Freeport liquefied natural gas export plant supported prices.
The Sleipner gas facility in Norway has been back in operation since last Friday after unplanned maintenance on August 1, which reduced flows by 5 mcm/d. New maintenance work has started at Visund, which will last for three days until August 4, with an impact on supply volumes of 7 mcm/d.
Prices of contracts with delivery in the relevant period, EUR/MWh, 01.08.2024
| Instrument | THE | CEGH | TTF | TGE/POLPX | CEEGEX/HUDEX | Average price |
|---|---|---|---|---|---|---|
| Day1 | 35,96 | 38,07 | 36,00 | 36,12 | 34,03 | 36,04 |
| M+1 | 37,02 | 38,35 | 36,96 | 36,71 | 38,65 | 37,54 |
| Q +1 | 40,14 | 40,94 | 39,71 | 40,31 | 41 | 40,42 |
| S +1 | 40,92 | 41,49 | 40,43 | 40,50 | 41,25 | 40,92 |
Month-ahead contracts at all analyzed hubs showed a different trend from spot prices, with an average increase of 4.31%. Quarter-ahead prices were 12.31% higher than spot prices on average. The season-ahead prices with an average value of EUR 40.92/MWh tended to increase compared to spot prices by an average of 13.68%.
On Thursday, the M+1 TTF reached its highest level in two months: EUR 36.96/MWh.
LNG prices in Asia remain higher compared to the European continent, which encouraged shippers to send volumes to the region. LNG demand in Asia reached a four-month high of 31.3 bcm in July.
The September futures for LNG in Asia, the JKM Platts Future Index, settled at USD 447.14 per thousand cubic meters. The LNG North West Europe Marker closed last Thursday at USD 389.15 per thousand cubic meters. Thus, the premium to European prices decreased to only USD 0.80/mBtu. USD/MMBtu from about USD 1.20/MMBtu a day earlier. USD/MMBtu a day earlier, making Europe a more attractive destination for many sellers given the distance and time involved.
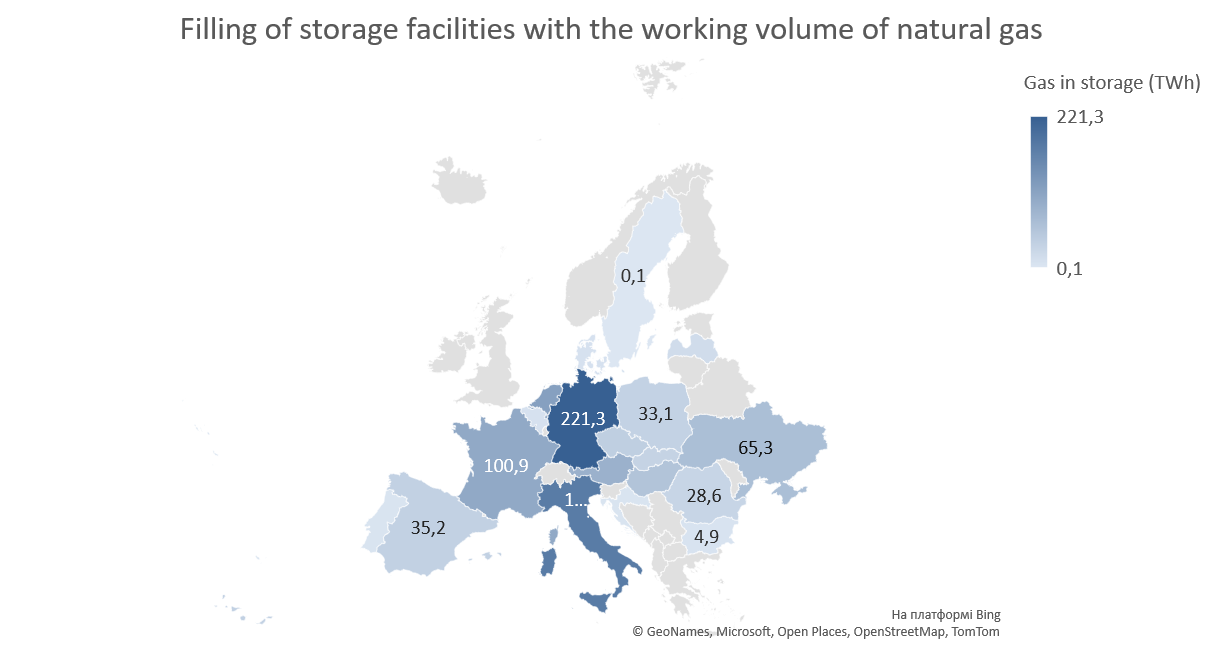
EU storage facilities are 85.12% full, according to the latest Aggregated Gas Storage Inventory, up 0.2% from the previous day, July 30, and only 5% short of the 90% target set by the EU for November 1.
In July, LNG imports to Europe and Turkey fell to their lowest level since September 2021. European LNG terminals operated at an average capacity of 70.66%.
As of July 24, LNG stocks in the EU amounted to 4.697 million cubic meters, according to the Aggregated LNG Storage Inventors.
The storage capacity of the largest LNG exporter, the United States, according to the latest EIA data as of July 26, 2024, was 3.249 billion cubic feet.
Gas balance in Ukraine
Last week, natural gas imports were present from Hungary and Moldova, averaging 1.9 mcm per day. Imports increased compared to the previous week, while exports from the customs warehouse were absent due to seasonality. Ukraine had about 10.95 billion cubic meters in storage. Injections amounted to approximately 28 million cubic meters per day.
Public procurement
Last week, 9 tender procedures were held for the purchase of natural gas by budgetary institutions. In total, 847 thousand cubic meters of natural gas worth UAH 11 million were sold at the largest tenders (top 10). The largest contract was awarded to Yasno+, which will supply 392 thousand cubic meters of natural gas to the Dnipro State Medical University at an initial price of UAH 12.96 per cubic meter. The average price was UAH 13.26 per cubic meter. Prices ranged from UAH 12.96 to UAH 13.53 per cubic meter, excluding VAT.
Interesting for theweek
The priority projects for the Ukrainian GTS Operator are to increase the capacity for transportation from European countries. This was stated by Andriy Prokofiev, Head of the Customer Relations Department of the GTSOU, during his speech at the Ukrainian Gas Open 2024 held on August 1 in Kyiv. "We see an opportunity to increase the capacity at the GTS entrance to transport gas to Ukraine from Poland, Hungary, Slovakia and Romania through Moldova. It is important to make these capacities not only technically guaranteed, but also competitive in terms of economics. Ukraine has a unique market offer - powerful gas storage capacities that strengthen Europe’s energy security. The realization of this depends on the related operators and their tariff policy," said Andriy Prokofiev. He also noted that the increase in tariffs for gas transportation through the Trans-Balkan route led to an almost 10-fold decrease in volumes compared to 2023. "That is why we are working and negotiating with our partners, the adjacent GTS operators, to create commercially attractive transportation routes together," summarized the GTSOU representative.
Azerbaijan’s SOCAR starts supplying gas to Slovenian Geoplin on August 1. The agreement was signed between the countries on July 17 this year. In SOCAR’s portfolio, this is the ninth country to which gas is supplied from Azerbaijan. It also supplies Bulgaria, Georgia, Greece, Italy, Turkey, Romania and Serbia. Last year, SOCAR’s exports amounted to 23.8 billion cubic meters, 11.5 billion cubic meters were sent to Europe.


