

Gas price: Ukraine and Europe. Market overview January 22 - 26, 2024

Gas price: Ukraine and Europe. Market overview
During the last week, natural gas prices in Ukraine did not undergo significant fluctuations, stable trading activity was observed.
Ukrainian Energy Exchange
Last week, the February, January 2024 resource was traded. In total, positions for the purchase and sale of natural gas were formed by 5 companies: JV BNK, Naftogaz Trading, Ukrnafta, Kraft Energy, JSC Kyivvodokanal.
Starting prices of resources had different trends during the week. As a result, as of Friday, the average starting price of the UGS resource was lower than Monday by 0.95%.
Over the last week, sell and buy positions were implemented. A total of 5920 thousand cubic meters of natural gas were sold, 5000 thousand cubic meters of resource in February in GTS was sold by Ukrnafta at a price of UAH 11,750 excl. VAT. In addition, 600 thousand cubic m of resource in January from UGS was purchased by Naftogaz Trading at prices in the range of UAH 11,800-11,850 excl. VAT, also 420 thousand cubic meters of resource was purchased from the commercial gas metering unit by Kyivvodokanal in February.
On the short-term natural gas market of UEEX, participants formed applications in GTS and UGS. The sale of gas took place on the within-day market. In total, 10 agreements with a total volume of 78 thousand cubic meters were concluded. During the week, the short-term market recorded a decrease in price. Marginal prices formed based on the results of the auctions are shown in the graph below.
European market
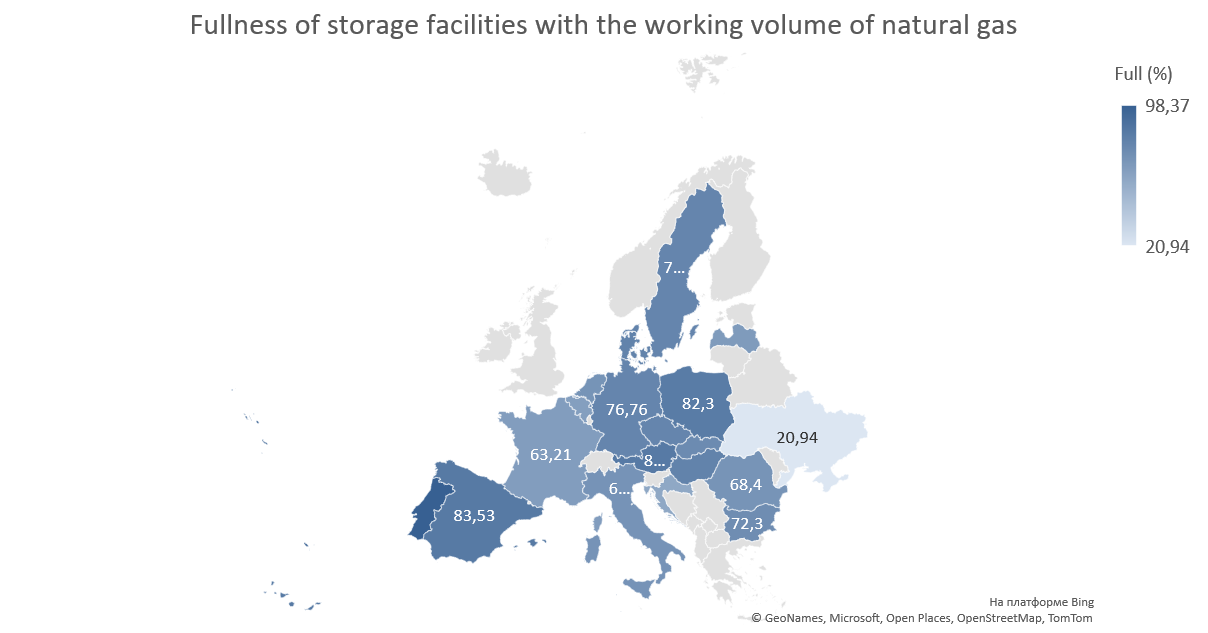
Natural gas prices on the Ice Endex were lower last week, except for Thursday, when there was a threat of lower LNG exports and a possible shortage of the resource in the market, as well as cold weather in Germany and France. The weekly average value of natural gas prices has continued to decline since November 2023, and on Friday, January 26, the benchmark TTF M+1 hit a new six-month low. Temperatures are expected to moderate across Europe in the coming weeks, but will remain above average for this time of year. As a result, demand from the heating sector remains weak. Weak demand and relatively full gas storage facilities, as well as a tendency to maintain heavy import volumes, combined to lower prices in Northwest Europe and the Mediterranean.
March LNG futures in Asia, the JKM Platts Future index, traded at USD 336 per thousand cubic meters last Thursday, January 25. Market experts, assessing the impact of the events in the Red Sea and traveling on longer routes on sales to Asia, see the negative consequences of this crisis first in shipping rates, and then in gas prices. Considering that consumption in Asia grew by 25 billion cubic meters last year, the 20 billion cubic meters of additional LNG production capacity that should be commissioned in 2024 worldwide is estimated to be insufficient and does not provide flexibility in the option if the Asian demand will remain high.
Futures for LNG delivered to North-West Europe (LNG North West Europe Marker) traded at USD 296 per thousand cubic meters.
The level of gas storage in the EU fell to 73.04% on January 24, according to data from the Aggregated Gas Storage Inventory.
Market participants are showing subdued buying interest given current storage levels.
European LNG terminals operated with an average capacity of 70.1%.
The storage fill level of the largest LNG exporter, the United States, according to the latest EIA data as of January 19, 2024, was 2.856 billion cubic meters ft. Exports of LNG from the US in January amounted to 5.34 million tons, increasing by 1.68 million tons for the week and accounting for 61% of exports in December. About 41% of the volumes were sent to Europe, 8% to Asia, 3% to North America and 1% to South America, the rest were not nominated.
Contracts for a month ahead in all analyzed hubs had the same trend in terms of spot prices – an average price increase of 2.68%. Quarter-on-quarter prices were higher than spot prices by an average of 5.96%. Prices for the season in advance with an average value of 31.54 EUR/MWh had a tendency to increase compared to spot prices by an average of 11.37%.
On the adjacent oil market, the escalating situation in the Red Sea is raising concerns about European oil supplies and forcing companies to change routes around South Africa. Brent traded at USD 81.99 per barrel on Friday, December 26.
Prices of contracts with delivery in the corresponding period, EUR/MWh, 25.01.2024
| Instrument | THE | CEGH | TTF | TGE/POLPX | CEEGEX/HUDEX | Average price |
|---|---|---|---|---|---|---|
| Day1 | 27,63 | 27,95 | 27,42 | 31,43 | 26,60 | 28,21 |
| M+1 | 28,38 | 28,52 | 27,79 | 32,77 | 27,41 | 28,97 |
| Q+1 | 29 | 29,77 | 28,46 | 32,80 | 29,32 | 29,87 |
| S+1 | 29,27 | 30,07 | 28,76 | 40,05 | 29,53 | 31,54 |
Gas balance in Ukraine
Imports of natural gas last week were almost non-existent. Export flows from the "customs warehouse" to neighboring countries were observed. Compared to previous periods, exports slightly decreased, remaining at an average level of 13.53 million cubic meters per day. Ukraine’s storage facilities contained 10.73 billion cubic meters, daily sampling decreased to 84 million cubic meters per day - due to warming.
Public procurement
Last week, 15 tender procedures for the purchase of natural gas by budgetary institutions and state enterprises were held. In total, 262,000 cubic meters of natural gas of the largest tenders (top-10) were sold in the amount of UAH 3.1 million. The largest contract was received by ERDAZ, which will supply one of the military units with 90,000 cubic meters of natural gas at the initial price of UAH 11.72/cubic meter. The average price was UAH 13.03 per cubic m. Prices ranged from UAH 11.72 to UAH 13.71 per cubic m.
Interesting for the week
DTEK Akhmetova wants the state to lift the ban on gas exports. The largest private gas production company of Ukraine is counting on the fact that the Cabinet of Ministers will review the ban on gas exports. According to DTEK, Ukraine cannot afford to live in a closed market. Maksym Timchenko also noted that for the company, as a market player, it is not an end in itself to extract gas and take it to Europe, but on the contrary, this year it itself used the possibility of gas storage in Ukraine, reports Energobusiness.
Qatar has informed some European buyers of delays and postponed shipments, the report said, citing traders with knowledge of the matter. Traders said Qatar was altering global supplies to meet contractual obligations by diverting supplies from elsewhere and swapping existing cargoes near Europe, according to the report. According to the report, since January 15, Qatar has diverted at least six shipments destined for Europe around the Cape of Good Hope in southern Africa instead of the shorter route through the Red Sea and the Suez Canal, according to vessel tracking data compiled. Qatar has not cut exports, even though some shipments are taking longer to reach their destinations, the report said.
According to the International Energy Agency’s (IEA) latest forecast, global gas demand could grow by 2.5% in 2024, following "unusually mild temperatures" in 2023, when global gas demand grew by just 0.5%. World demand is likely to grow by 100 billion cubic meters, or 2.5%, up to 4190 billion cubic meters this year as prices stabilize after recent volatility.


