Gas price: Ukraine and Europe. Market overview February 9 - 13, 2026
In the "Medium and Long-Term Market" section of the UEEX, trading in the February 2026 resource continued. In total, positions for the sale of natural gas were formed by 5 companies: Ukrnafta, MC Ukrnaftoburinnia, LTK Electrum, ONK-Energy, Tepla. The section sold 2.4 million cubic meters of natural gas. The main type of natural gas sold was natural gas supplied to the gas transmission system. The prices of the sold items were in the range of 20,700-21,100 UAH/thousand cubic meters excluding VAT.
In addition, Ukrnafta sold 7 million cubic meters of natural gas in the differential trading section with a premium of 1.36-3.92 euros to TTF.
On the short-term natural gas market of the UEEX, participants formed orders on the within-day market and the day-ahead market. In total, 42 deals were concluded with a total volume of 3,429 thousand cubic meters.
Prices on European gas markets have remained elevated since early January, supported by prolonged cold weather, limited European gas storage capacity, and strong links to global commodities. Given the projected further cooling, gas forward contracts remain sensitive to short-term risks.
Gas markets continued to stabilize in the second week of February after recent volatility. Investment fund activity was a key driver of volatility. According to the latest Commitment of Traders report, funds reduced short positions in TTF by 37 TWh and exited long positions by 52 TWh.
Two more cold spells are expected in February, leading to increased heating demand across northwestern Europe and the UK. Weather-related risk is not yet gone. Cold conditions are supporting demand and this support is affecting forward contracts.
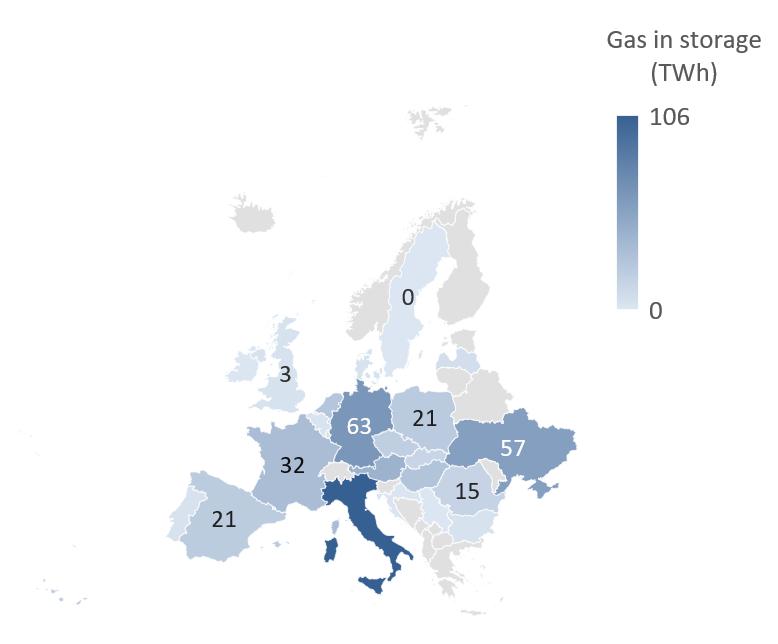
EU gas storage stocks are at an eight-year low of 35.21% as of 11/02/2026, and North-West Europe is set to reach below 5% fill by the end of the winter season. For example, UK storage levels are 17% below the 5-year seasonal average, and the gas market remains highly sensitive to weather revisions. The lower limit of winter stocks increases replenishment needs and increases risks to the forward balance, amplifying the impact on prices of relatively small revisions to weather forecasts.
Low inventory concerns continue to ease as LNG supplies remain ample. Gas supplies to U.S. terminals remain normal after several plant outages in late January. Tight supply schedule shows LNG cargoes are adequate from Feb. 14-24.
Natural gas imports from Europe averaged about 25.3 million cubic meters per day (+5.5%) and had a growing trend. Imports were present from all neighboring European countries. The basis of imports was the Polish direction. Exports from customs warehouses were present in the amount of about 1.5 million cubic meters per day, in the direction of Poland and Moldova. In the storage facilities of Ukraine there were 10.00 (-3.38%) billion cubic meters of natural gas. Withdrawals were about 45 million cubic meters per day.