Gas price: Ukraine and Europe. Market overview February 23 - 27, 2026
In the "Medium and Long-Term Market" section of the UEEX, trading in the resource continued in February and March 2026. In total, positions for the sale or purchase of natural gas were formed by 6 companies: Ukrnafta, Ukrnaftoburinnia, JV BNK, Kyivvodokanal, LTK Electrum, Energo Zbut Trans. The section sold 15.71 million cubic meters of natural gas, which is 10 times more than the previous week. Natural gas was sold with deliveries to the GTS and UGS, in February and March. The positions of two selling companies - Ukrnafta and Ukrnaftoburinnia - were mostly successful. The prices of the sold positions were in the range of 18,833-20,833 UAH/thousand cubic meters excluding VAT.
On the short-term natural gas market of the UEEX, participants formed orders on the within-day market and the day-ahead market. In total, 29 deals were concluded with a total volume of 1,087 (+26.88%) thousand cubic meters.
Fundamentals in Europe remained weak amid mild weather and stable gas supplies. Traditionally, the period from late March to May sees a decline in demand for heating and cooling, often leading to seasonal price declines. This makes spring one of the most attractive times of year to enter into forward contracts. Price levels may be relatively attractive before summer heat or unexpected supply disruptions lead to renewed volatility.
Thursday’s session on gas markets was characterized by high volatility in both directions across the curve. The day started on a negative note with supply fundamentals remaining stable and higher temperatures forecast through March 26, reducing heating demand and expectations for storage withdrawals, leading to lower prices. The losses were offset by news of failed talks between the United States and Iran, with Iran seemingly adamant that it will not dismantle any nuclear facilities. With European storage currently 17% below its 5-year average and heavily reliant on spot LNG cargoes, any risk of disruption through the Strait of Hormuz poses risks both in the short term in terms of supply disruptions and in the long term in terms of the potential impact on the rate of storage replenishment. Thus, the April contracts, as well as the summer and winter contracts, closed 3-4% higher than the previous day.
On Friday, the M+1 contracts turned around and the price decreased.
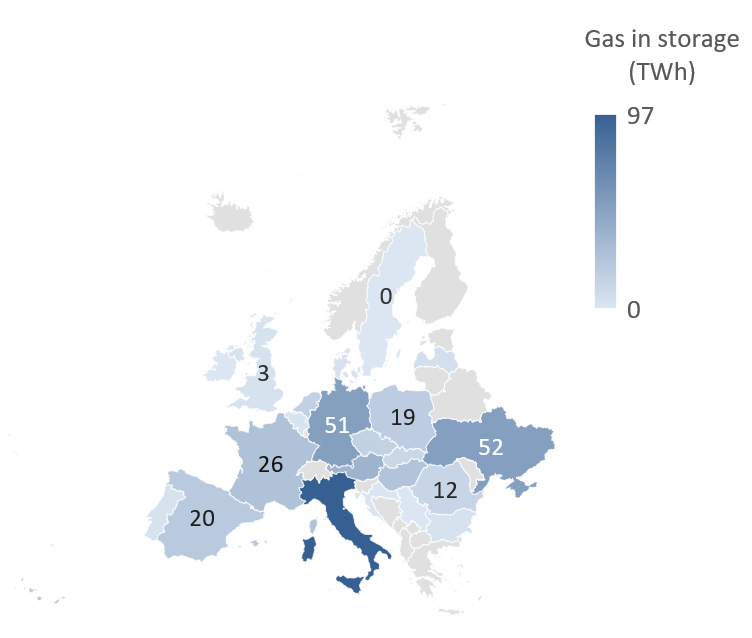
The total occupancy of EU gas storage facilities by February 25 decreased to 30.19%. The market expects lower withdrawal rates for the rest of the winter period.
Natural gas imports from Europe averaged about 25.2 million cubic meters per day and were virtually unchanged from the previous week. Imports were present from all neighboring European countries. The basis was the Polish direction. Exports from the customs warehouse were present only on Friday, in the amount of 1 million cubic meters, in the direction of Moldova. In the storage facilities of Ukraine there were 9.78 (-2.35%) billion cubic meters of natural gas. The withdrawal was about 15 million cubic meters per day.