Gas price: Ukraine and Europe. Market overview February 2 - 6, 2026
In the "Medium and Long-Term Market" section of the UEEX, trading in the February 2026 resource continued. In total, positions for the sale of natural gas were formed by 7 companies, including Ukrnafta, MC Ukrnaftoburinnia, LTK Electrum, ONK-Energy. The section sold 4.1 million cubic meters of natural gas. The main type of natural gas sold was natural gas supplied to underground storage facilities. The prices of the sold items were in the range of 20,900-21,200 UAH/thousand cubic meters excluding VAT.
In addition, Ukrnafta sold 2 million cubic meters of natural gas in the differential trading section with a premium of 0.62-0.95 euros to TTF.
On the short-term natural gas market of the UEEX, participants formed orders on the within-day market and the day-ahead market. In total, 58 deals were concluded with a total volume of 3,284 thousand cubic meters (+353%).
Volatility on energy markets continued in the first week of February, with supply and demand fundamentals sometimes appearing secondary to geopolitical and macroeconomic factors. Milder weather forecasts, improved LNG supply and declining demand contributed to bearish movement at the start of the week.
Factors in the broader commodity complex also played a role. Tighter-than-expected policy by the US Federal Reserve led to a stronger US dollar, which pushed down prices for US dollar-denominated commodities, including gold, silver and copper.
As metals traders quickly closed their positions, the panic spread to other commodities, leading to a broader sell-off. As a result, the value of monthly gas contracts fell sharply in just the last two sessions on Tuesday, February 3.
There was a slight recovery on Wednesday and Thursday. Prices rose across the board on Thursday on the back of a predicted cold snap in Europe and the UK. Temperature forecasts had previously indicated a colder than average end to the 25/26 winter season, and forecasts published in late January had indicated almost 6 consecutive weeks of below-average temperatures. Worsened forecasts received at the end of the week have heightened concerns about demand across Europe.
Demand for gas for electricity generation has increased, affecting day-ahead and month-ahead contracts. US and Iranian delegations met in Oman on Friday, the 6th, to discuss Iran’s nuclear program. Tensions between the US and Iran continue to weigh on risks related to the Strait of Hormuz in gas contracts.
Normalization of weather in the US led to a 25% drop in the monthly Henry Hub contract, the steepest one-month drop for any futures contract since 1995. Near-record gas deliveries to US liquefaction plants eased European supply concerns.
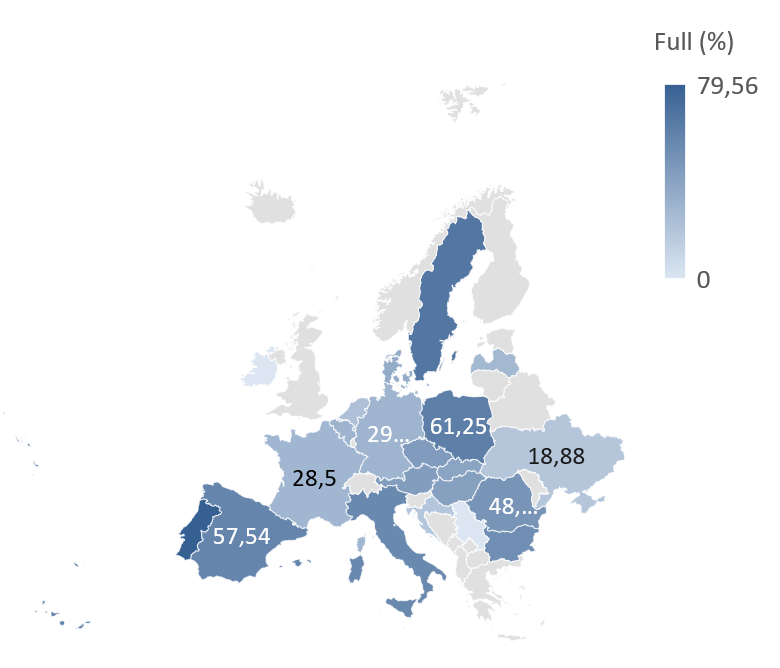
European storage capacity is at 39% and is forecast to fall to around 23% in the spring, the lowest level since 2018.
Natural gas imports from Europe averaged about 23.98 million cubic meters per day (+9.85%) and had a growing trend. Imports were present from all neighboring European countries. The basis of imports was the Polish direction. Exports from customs warehouses were present in the amount of 3.5 million cubic meters per day, in the direction of Poland and Moldova. In Ukrainian storage facilities there were 10.35 (-3.45%) billion cubic meters of natural gas. Withdrawals amounted to about 67 million cubic meters per day.