Gas price: Ukraine and Europe. Market overview February 16 - 20, 2026
In the "Medium and Long-Term Market" section of the UEEX, trading in the resource continued in February and March 2026. In total, positions for the sale or purchase of natural gas were formed by 9 companies: Ukrnafta, MC Ukrnaftoburinnia, Ukrzaliznytsia, Tepla, JV BNK, etc. The section sold 1.58 million cubic meters of natural gas. Natural gas was sold exclusively with supply to the GTS in February and March. The prices of the sold items were in the range of 19718-21150 UAH/thousand cubic meters excluding VAT.
On the short-term natural gas market of the UEEX, participants formed orders on the within-day market and the day-ahead market. In total, 36 agreements were concluded with a total volume of 826 thousand cubic meters.
Gas markets started the week with a decline amid a sharp improvement in temperature forecasts for Europe and the UK by the end of February. In addition to the growth of wind generation, this should limit the demand for gas in the power sector.
Geopolitical risk premiums were buoyed by optimism Wednesday afternoon when Iran temporarily closed part of the Strait of Hormuz, apparently in response to the increased U.S. military presence in the Arabian Sea. Iranian news agencies reported that parts of the strait were closed for several hours (for shipping safety) to allow the Islamic Revolutionary Guard Corps to conduct military exercises. As a result, gas prices strengthened across the curve in the final session on Thursday, with the Dutch M+1 contract up 16% in within-day trading, supported by renewed tensions between the US and Iran, further increasing geopolitical risk and facilitating rapid contract execution. Price increases became progressively more muted further down the curve, with the impact largely disappearing starting with contracts for the summer of 2027. Possible delays in LNG supplies, the development of trade agreements, and the expansion of the global economy should not be discounted, as these are all factors that contribute to growth in the long term.
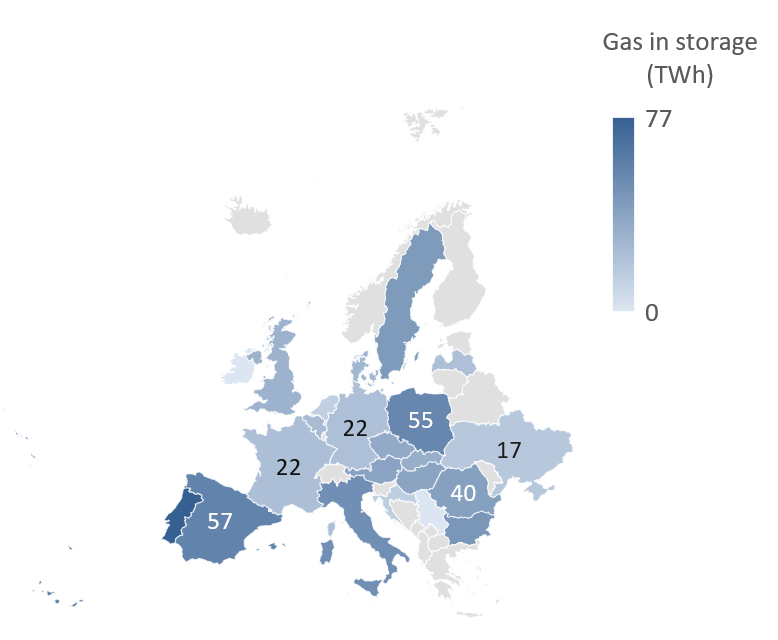
Warmer temperatures next week will support EU gas storage levels, which are currently 33% full, compared to a 5-year average of ~49%. Key storage countries Germany, France and the Netherlands are also depleted – 23%, 23.6% and 14.3% respectively, with the Netherlands facing potential full depletion by the end of winter.
Future growth in US LNG supplies continues to ease concerns. Golden Pass (US) is close to starting LNG production, receiving 300 million cubic feet of gas on Wednesday, February 18; the market is pricing in the possibility of first shipments as early as early March. Importantly, this is one of the largest export terminals in the US, so every step towards commissioning has a significant impact on the expectations of the LNG balance for Europe.
Natural gas imports from Europe averaged about 25.3 million cubic meters per day and were unchanged from the previous week. Imports were present from all neighboring European countries. The basis of imports was the Polish direction. Exports from the customs warehouse were present in the amount of about 1.3 million cubic meters per day, in the direction of Moldova. Ukraine’s storage facilities contained 9.78 (-2.2%) billion cubic meters of natural gas. The withdrawal was about 45 million cubic meters per day.