

Gas price: Ukraine and Europe. Market overview February 12 - 16, 2024

Gas price: Ukraine and Europe. Market overview
Last week, natural gas prices in Ukraine fluctuated, following the trends of European hubs.
Ukrainian Energy Exchange
Trading in the resource continued in February 2024 and March 2024. Overall, positions for the purchase and sale of natural gas were formed by 2 companies: Ukrnafta and Naftogaz Trading.
Starting prices of resources decreased throughout the week. As a result, as of Friday, the average starting price of resources in UGS facilities was 0.44% lower than on Monday.
Last week, the Naftogaz sold its purchase positions. In total, 33,600 thousand cubic meters of natural gas were sold. All volumes were sold by Naftogaz Trading at prices in the range of UAH 11714-11832 excluding VAT.
On the short-term natural gas market of the UEEX, participants placed bids in the GTS and UGS facilities. Gas was sold on the within-day market. A total of 67 thousand cubic meters of gas was sold.
The marginal prices formed as a result of the auction are shown in the chart below.
European market
Last week, M+1 gas prices at the Dutch TTF hub reached a new seven-month low, the lowest level since July last year. Among the main reasons include mild weather and weak demand. An unplanned outage at the Norwegian gas processing plant Kollsnes led to a 23.1 million cubic meters per day reduction in gas supplies to Europe, according to TSO Gassco. In addition, France’s Engie has reduced gas supplies from two French LNG terminals (11.5 billion cubic meters of gas per year in total) to 12 GWh/day since the start of the strike on February 8, which continues. But these events did not affect the downward price trend.
The March futures for LNG in Asia, the JKM Platts Future index, traded last Thursday, February 15, at USD 335 per thousand cubic meters. The decline in Asian prices occurred amid weak competition for cargo during the holiday week in most of Asia, ANZ analysts say. Prices for the monthly APR 24 contract for Asian LNG on JKM last week reached USD 303 per thousand cubic meters, the lowest level since April 28, 2021.
Prices of contracts with delivery in the respective period, EUR/MWh, February 15, 2024
| Instrument | THE | CEGH | TTF | TGE/POLPX | CEEGEX/HUDEX | Average price |
|---|---|---|---|---|---|---|
| Day1 | 24,87 | 26,02 | 24,47 | 26,95 | 24,79 | 25,42 |
| M+1 | 25,32 | 25,95 | 24,99 | 30,08 | 25,8 | 26,43 |
| Q+1 | 25,64 | 26,59 | 25,36 | 30,02 | 25,58 | 26,64 |
| S+1 | 25,91 | 26,85 | 25,6 | 31,05 | 25,8 | 27,04 |
Month-ahead contracts at all the analyzed hubs showed a different trend in relation to spot prices, with an average increase of 3.87%. Quarter-ahead prices were 4.70% higher than spot prices on average. The seasonal forward prices with an average value of 27.04 EUR/MWh tended to increase compared to the spot prices by an average of 6.25%.
Futures for LNG delivered to Northwest Europe (LNG Northwest Europe Marker) were trading at USD 293 per thousand cubic meters.
On the demand side, last week’s temperatures in Europe were about 6-10 degrees above average, and the weather forecasts are milder and windier, which should lead to a decrease in gas demand.
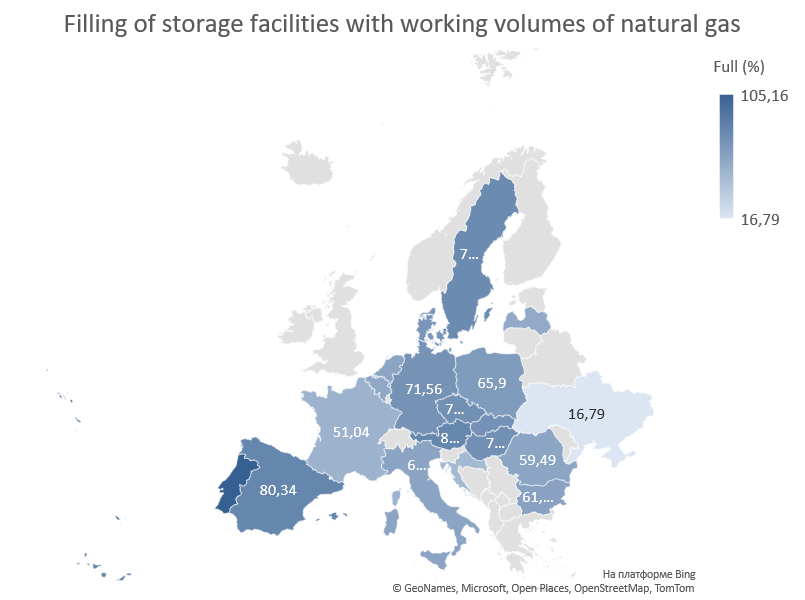
The level of gas storage in the EU has fallen to 65.94% of capacity, according to the latest Aggregated Gas Storage Inventory. LNG stocks in the EU amounted to 3.796 million cubic meters as of February 14, according to the Aggregated LNG Storage Inventory.
European LNG terminals operated at an average capacity of 69.84%. The price of LNG deliveries from tankers (or DES) to northwestern Europe in M+1 fell last week for six days in a row, following a decline in prices at gas hubs.
According to the latest EIA data, the storage level of the largest LNG exporter, the United States, as of February 9, 2024, was 2.535 billion cubic feet.
According to Shell’s industry forecast, the growth in LNG supply and demand could vary from 7 to 20 million tons in 2024. Supply growth will be driven by increased supply from the US, while demand growth will be focused mainly on Asia and China, as the industrial transition from coal to gas gathers pace in China and South and Southeast Asian countries use more LNG to support their economic growth. Demand for LNG is expected to grow by more than 50% by 2040.
On the related oil market, Brent crude prices continue to be supported by OPEC+ production cuts and the current situation in the Middle East, and on Friday, February 16, crude was trading at USD 82.03 per barrel.
Gas balance in Ukraine
There were no imports of natural gas last week. Export flows from the customs warehouse to neighboring countries were observed. Exports decreased compared to previous periods, remaining at an average level of 8.95 mcm per day. Ukraine had about 9.5 billion cubic meters in storage facilities, and the daily withdrawal decreased to 44 million cubic meters per day due to warming.
Public procurement
Last week, five tender procedures were held for the purchase of natural gas by budgetary institutions and state-owned enterprises. In total, 127 thousand cubic meters of natural gas worth UAH 1.51 million were sold at the largest tenders. The largest contract was awarded to GAZENERGO-TRADE, which will supply 66 thousand cubic meters of natural gas to Zhashkiv Multidisciplinary Hospital at an initial price of UAH 11.88 per cubic meter. The average price increased and amounted to UAH 12.03 per cubic meter. Prices ranged from UAH 11.38 to UAH 12.64 per cubic meter, excluding VAT.
Interesting for the week
Last Thursday, the EC announced the first medium-term joint tender for gas purchases. Companies are invited to participate in the EU’s first medium-term joint gas tender by registering their application for even several six-month periods from April 2024 to October 2029 on the AggregateEU platform by February 21. The platform operator Prisma will aggregate this demand and put it out to tender to international suppliers, except for Russian companies, from February 26 to 27. The tender is a voluntary continuation of 4 rounds of short-term monthly demand tenders conducted through the same platform in 2023.
The Cabinet of Ministers approved the Procedure for the use or sale of a part of the output, including natural gas, which remains in the state’s ownership under a production sharing agreement. The Procedure defines the relationship between the investor, the State Service of Geology and Subsoil of Ukraine, which is the authorized body for the implementation of production sharing agreements, and the subsidiary company Gaz Ukrainy of Naftogaz of Ukraine. The procedure provides for a clear and transparent mechanism for the sale of the state share of production. In practice, this will allow for an efficient allocation of resources, which will allow Ukraine to benefit even more from the signed agreements.


