Gas price: Ukraine and Europe. Market overview December 8 - 12, 2025
In the section short-term and long-term market of UEEX continued trading of December 2025 resource. In total, positions for the purchase and sale of natural gas were formed by 3 companies: Ukrnafta, MC Ukrnaftoburinnia, LTK Electrum. Section sold 5,5 million cubic meters of natural gas, which is 3,7 times higher than last week. Natural gas with delivery to underground storage facilities in December was mainly sold. The prices of sold positions were in the range of 19,650-20,100 UAH/thousand cubic meters excluding VAT, which is lower than last week.
GTS Operator of Ukraine also conducted purchases in the "Transborder" and "Customs Warehouse" sections. About 30,3 million cubic meters of natural gas (-9%) were purchased with transmission at the border point at prices of sold positions in the range of 34,7-35,65 EUR/MWh, which is approximately 1 EUR lower than the price range of last week.
At UEEX short-term natural gas market participants submitted bids on the within day market and the day-ahead market. A total of 45 (+52%) deals were concluded with a total volume of 2080 (+26%) thousand cubic meters.
Throughout the second trading week of December, both short-term and long-term gas futures markets remained in a state of consolidation after last week’s sharp decline, as bearish fundamental weather factors outweigh any other market factors. On December 10 and 11, local lows since April 2024 were updated amid mild weather and sufficient supply. The bearish trend continued in the UK gas market, with gas prices further down the curve reaching a 44-month low. Sensitivity to further TTF declines is increasing, according to Reuters. Risk balance is skewed toward low volatility in mild weather conditions, with weather updates for December 15–20 being the key risk factor.
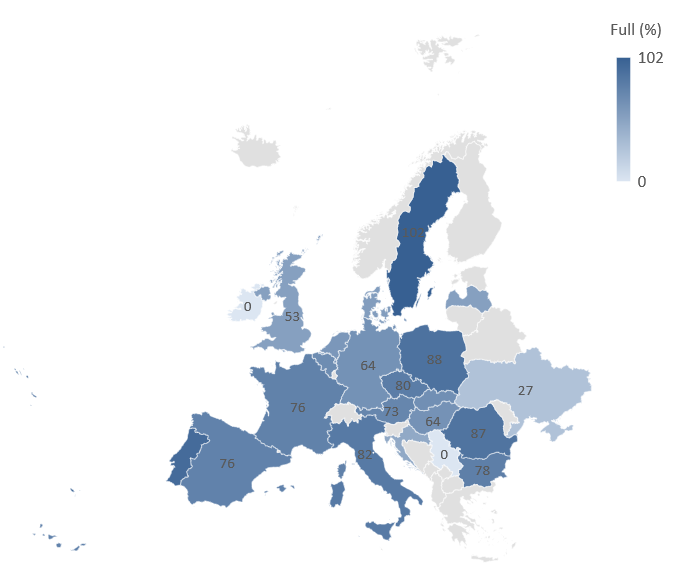
There are still signs that there will be no cold snap during the two weeks of industrial shutdowns over Christmas, which significantly weakens demand. The latest temperature forecasts indicate above-average temperatures in northwestern Europe until the end of December. Gas withdrawals from pan-European storage facilities have decreased to approximately 0,3% per day, with capacity utilization hovering above 70%, which is lower than last year’s figures.
Record November LNG exports from the US remained strong in early December. Along with LNG, stable shipments from Norway, which are close to their peak level of 340 million cubic meters per day, are putting pressure on the forward end of the curve.
According to the latest Commitment of Traders report, investment funds are increasing their net short positions on the main European gas benchmark, TTF. Last week, funds that do not typically take physical delivery of gas but generate income by entering and exiting positions had a net short position of 50 TWh of Dutch gas. This week, funds increased that net short position to 84 TWh.
Natural gas imports from Europe averaged 23,6 million cubic meters per day. Import came from all neighboring European countries. Hungarian and Polish directions accounted for the bulk of imports. Exports from customs warehouses to Moldova amounted to 1 million cubic meters on December 10-11. There were about 12,8 billion cubic meters of natural gas (-0,8%) in Ukrainian storage facilities. Withdrawals amounted to 20 million cubic meters per day.