Gas price: Ukraine and Europe. Market overview December 15 - 19, 2025
In the “Medium- and Long-Term Market” section of UEEX trading in December 2025 and January 2026 resources continued. In total, five companies formed positions for the purchase and sale of natural gas, including Ukrnafta, MC Ukrnaftoburinnya, and LTK Elektrum. Section sold 9,6 million cubic meters (+74,55%) of natural gas. Most of the resources were sold with delivery to underground gas storage facilities in December. The prices of the positions sold ranged from UAH 19830 to UAH 20100 per thousand cubic meters excluding VAT, which is approximately the same as last week.
Ukrainian GTS Operator also conducted procurement in the “Cross-border” and “Customs warehouse” sections. Approximately 33,72 million cubic meters of natural gas (+11,29%) were purchased with transfer at the border point at prices ranging from EUR 34,65 to EUR 35,75 per MWh.
On UEEX short-term natural gas market participants submitted applications on the intraday market and the day-ahead market. A total of 48 (+3) agreements were concluded with a total volume of 2,690 (+30%) thousand cubic meters.
Session on Wednesday, December 18, was marked by a five-year low in natural gas prices in China, reducing the risks of competition from the Asian LNG supply market. There is significant potential for growth in supplies to both UK and Europe. New wave of LNG supplies is not a “panacea” for high gas prices in Europe, and prices may be subject to fluctuations even in the future period of oversupply.
Weather forecasts indicate that wind and temperatures during the holiday week will be below seasonal norms, although any optimism associated with the worsening situation has been tempered by the stability of supplies. Key growth factor remains the forecast of low temperatures (below seasonal norms) in January in Europe, which continues to support demand for heating.
TTF M+1 prices remained within a narrow range. ICE reported expected record annual trading volumes on TTF (>103 million contracts).
At the end of the review week, prices rose slightly amid colder weather, but overall remained depressed by weak demand and balanced by LNG and Norway.
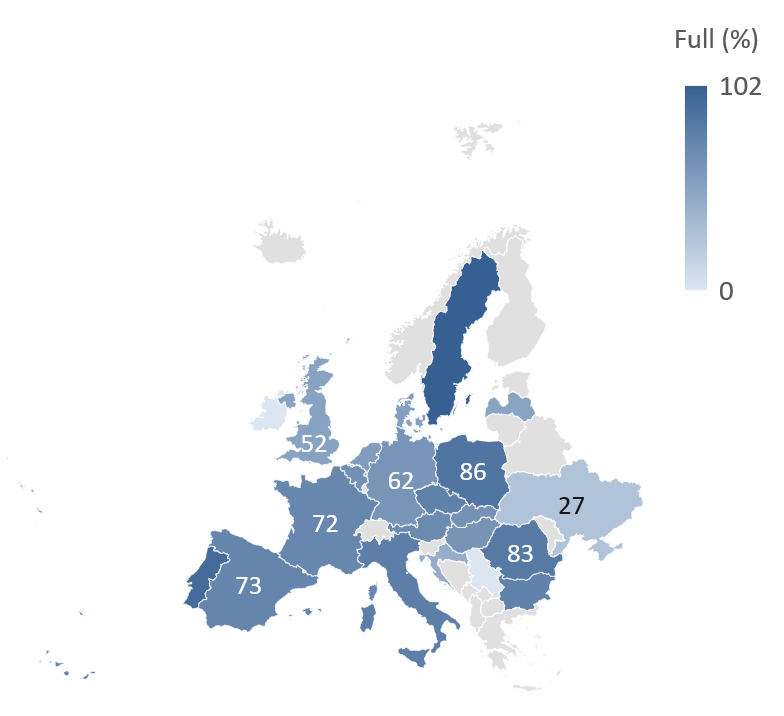
Filling rate of pan-European storage facilities remains at 68,24% of capacity as of December 17, 2025, which is 10% less than a year earlier. Current estimates predict that gas stocks in EU storage facilities after winter will be around 34% (7% below average) based on typical withdrawal rates, but persistently low temperatures could lead to a decline in this level, sustaining demand for gas injection throughout the summer of 2026.
On Wednesday, European Parliament approved the EU’s initiative to end russian gas imports by the end of 2027, removing the penultimate legal hurdle to the ban. Under the agreement, EU will stop importing russian LNG by the end of 2026 and pipeline gas by the end of September 2027. As of October, Russia accounted for 12% of gas imports to EU, significantly less than 45% it accounted for before russia’s invasion of Ukraine in 2022.
Natural gas imports from Europe averaged 25 million cubic meters per day. Imports came from all neighboring European countries. Hungarian and Polish directions accounted for the bulk of imports. There were no exports. Ukraine’s storage facilities held approximately 12,7 billion cubic meters of natural gas (-0,8%). Withdrawals amounted to approximately 20 million cubic meters per day.