

Gas price: Ukraine and Europe. Market overview August 12 – 16, 2024

Gas price: Ukraine and Europe. Market overview
Over the last week, natural gas prices in Ukraine have been fluctuating, partly in contrast to the trends in European hubs.
Ukrainian Energy Exchange
Last week, trading in August and September 2024 continued. In total, 4 companies formed positions for the purchase and sale of natural gas: GTS Operator of Ukraine, Naftogaz Trading, Ukrnafta, and Electricity of China.
The starting prices of resources were growing throughout the week. As a result, as of Friday, the average starting price of August resources in the GTS was 0.18% higher than on Monday.
Last week, positions for sale were sold. In total, 12,100 thousand cubic meters of natural gas were sold. All volumes were sold by Ukrnafta and related to the September resource in the GTS (prepayment). The prices of the sold positions were in the range of UAH 14479.37-14800.
On the short-term natural gas market of the UEEX, participants placed bids in the GTS and UGS facilities. Gas was sold on the within-day market. A total of 20 deals were made with a total volume of 141 thousand cubic meters. During the week, prices on the short-term market increased. The marginal prices formed as a result of trading are shown on the chart.
European market
Gas prices have risen by more than 20% since the end of July. Last week, TTF gas futures on the ICE Front-Month market continued the upward trend observed in the previous week. The escalation of hostilities between Ukraine and Russia in recent days near Ukrainian gas storage facilities and gas supplies has raised concerns about possible reductions and disruptions in gas supplies to Europe through the region. In general, Russian gas continues to flow through Sudzha uninterrupted, with a nominal rate of 453 GWh/day, allaying market fears of potential damage at this gas interconnection point.
In addition, last week’s Norwegian gas exports were almost at full capacity and low LNG imports at European import terminals contributed to this increase in gas prices. Additionally, future supplies to Europe are threatened by the potential for a wider war in the Middle East, which could cut off the region’s energy exports.
September will be a critical maintenance period in Norway, when the Kårstø processing plant and its related infrastructure will be shut down for almost three weeks. This coincides with the closure of the Dornum and Nybro terminals, and the Langeled pipeline will also be closed during the first half of the month. Despite this, gas prices have remained stable, largely due to well-stocked storage facilities in Europe, which has eased fears of possible supply disruptions as winter approaches.
Prices of contracts with delivery in the respective period, EUR/MWh, 08/15/2024
| Instrument | THE | CEGH | TTF | TGE/POLPX | CEEGEX/HUDEX | Average price |
|---|---|---|---|---|---|---|
| Day1 | 38,57 | 40,44 | 38,60 | 38,31 | 37,36 | 38,66 |
| M+1 | 39,62 | 41 | 39,56 | 38,38 | 39,64 | |
| Q +1 | 42,8 | 43,66 | 42,33 | 43,61 | 43,10 | |
| S +1 | 43,59 | 44,19 | 42,97 | 43,91 | 43,67 |
Month-ahead contracts at all analyzed hubs showed a different trend from spot prices, with an average decrease of 18.14%. Quarter-ahead prices were 10.94% lower than spot prices on average. Season-ahead prices with an average value of EUR 43.67/MWh tended to decrease by an average of 9.77% compared to spot prices.
The price difference between continental Europe and the UK continues to widen. On Thursday, the NBP to TTF discount was 19.15 p/therm against 17.95 p/therm on the previous trading day. UK short-term gas prices fell by more than 1% on Thursday due to stable supply. The spot price of NBP closed at 78.00 p./therm. The price of gas for Win-2024 delivery increased by 1% to 111.50 p/therm, influenced by the escalation of the Russian war in Ukraine and concerns about insufficient LNG supplies for the winter.
Gas fundamentals continue to show a much weaker balance: Asian demand appears to be weakening, and LNG availability is expected to increase as a result. The September LNG futures in Asia, the JKM Platts Future index, rose and settled last Thursday at USD 457.45 per thousand cubic meters. The LNG North West Europe Marker closed last Thursday at USD 405.26 per thousand cubic meters.
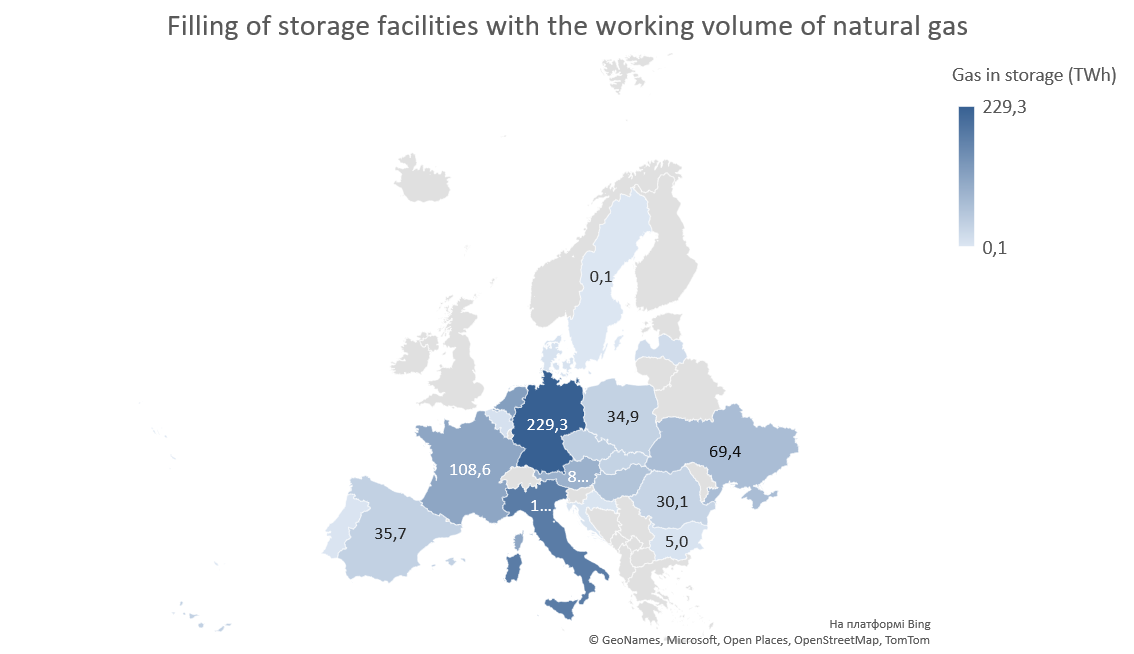
Storage facilities in the EU are 88.5% full, according to the latest Aggregated Gas Storage Inventory, an increase of about 1.8% compared to the week before.
European LNG terminals operated at an average capacity of 70.658%.
As of August 14, LNG stocks in the EU amounted to 4.538 million cubic meters, according to the Aggregated LNG Storage Inventors.
The storage level of the largest LNG exporter, the United States, according to the latest EIA data as of August 9, 2024, was 3.264 billion cubic feet.
Gas supplies through pipelines from Norway last Friday were at 331.4 million cubic meters per day, according to TSO Gassco.
On the related market, Brent crude oil prices rose by almost 2% on Thursday. On August 16, prices traded at USD 80.12 per barrel, amid lower demand from Chinese refineries, but showed weekly growth due to strong US economic data and ceasefire negotiations in the Middle East, which stimulated overall demand optimism.
Gas balance in Ukraine
Last week, natural gas imports from Hungary and Moldova averaged 0.8 mcm per day. Imports remained virtually unchanged compared to the previous week, while exports from the customs warehouse resumed, with a volume of up to 1.1 mcm per day. Ukraine had about 11.2 bcm in storage. Injections amounted to about 25 million cubic meters per day.
Intersting for the week
In July 2024, the GTS Operator of Ukraine purchased 29.9 million cubic meters of natural gas through trading on the UEEX, concluding 18 agreements with 10 sellers. This volume is sufficient to fully meet the current production and business needs of the Company. In just 7 months of 2024, GTSOU concluded 82 agreements for the purchase of 128.1 million cubic meters of natural gas. The operator is interested in expanding the range of counterparties and building long-term mutually beneficial relations with the market. The company plans to actively offer participants a full list of procurement products, including non-resident participants with the delivery of “border of Ukraine” and with the delivery of UGS “Customs warehouse”.
Russia and Ukraine plan to continue pipeline gas supplies to Europe despite ongoing fighting near the main cross-border transit point. Bloomberg writes about this with reference to knowledgeable sources. Concerns about supply disruptions have already led to higher gas prices in Europe, Forbes reports. At the same time, any accidental damage to key infrastructure at the Suzhda gas receiving station could halt supplies, one of the sources said. According to the two sources, the border crossing point has been under the control of the Ukrainian armed forces since the invasion.


