Gas price: Ukraine and Europe. Market overview August 10 - 14, 2026
In the "Medium and Long-Term Market" section of the UEEX, trading in the August 2026 resource in the GTS and UGS continued. In total, positions for the sale or purchase of natural gas were formed by 7 companies: GSC Naftogaz Trading, GTS Operator of Ukraine, Ukrnafta, LTK Electrum, etc. In total, 25.3 million cubic meters of natural gas were sold in the section - a resource for August 2026. The purchase positions from the Operator of the GTS of Ukraine, Ukrzaliznytsia and Concern "MTM" were successful.
On the short-term natural gas market of the UEEX, participants formed orders on the within-day market, in the GTS and UGS. In total, 57 exchange agreements were concluded with a total volume of 2,047 thousand cubic meters.
TTF price dynamics returned to growth after a decline in early August, when prices fell to 52.4 EUR/MWh. The past week has seen a rapid recovery in quotes on the European gas hub TTF as hopes for a peaceful resolution to the shipping row in Hormuz were dashed again after Iran made it clear that a deal with Oman alone would not be enough.
The underlying front-month futures on the Dutch TTF hub started the week with a sharp jump of 8.09% on Monday (to 61 EUR/MWh) and held steady above 60 EUR/MWh throughout the week. Thus, the market has returned to the psychological level, which indicates that traders remain highly nervous and sensitive to any news regarding supply. The market does not expect a significant reduction in energy prices in the near future. Over the past 8 weeks, hedge funds have accumulated the largest net long position (bets on price growth) on Dutch hub TTF contracts. This is evidence that speculative and institutional investors continue to build into their strategies a further increase in gas prices in Europe, preparing for potential shortages as the winter heating season approaches.
Overall, European natural gas prices have increased by more than 11.3% over the past month, and year-on-year (compared to the same period last year) quotes have soared by 95,6%.
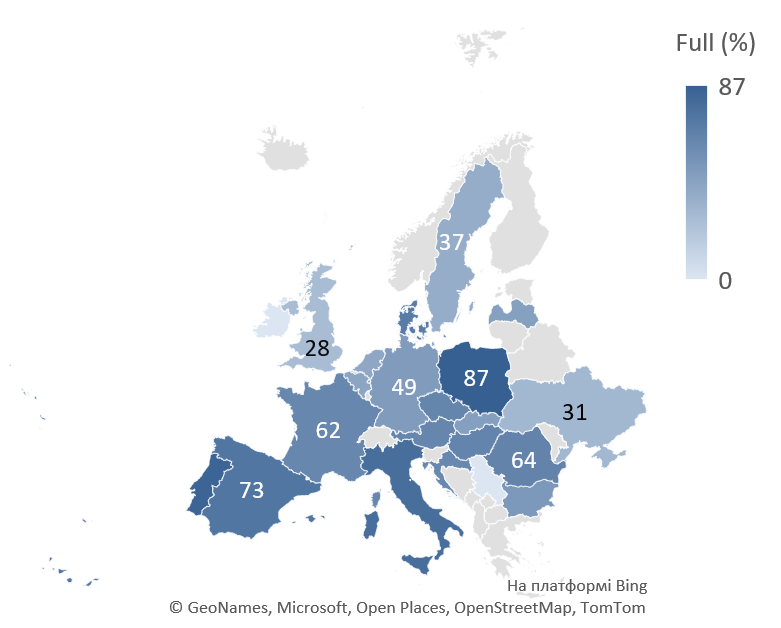
Monday also saw an unwelcome reduction in winter supplies from Norway as scheduled maintenance at the Ormen Lange field was extended by 4 months. Originally, 8.9 million cubic meters per day were to be shut down from July 13 to October 1. However, Norwegian gas system operator Gassco has revised the details of the shutdown, indicating that it will now last until February 1, 2027. The aggregate fill rate of Europe’s natural gas storage facilities remains consistently below 60%, standing at 59.66% according to the latest AGSI data as of August 12, 2026. This is the lowest occupancy rate for a year since records began in 2014, down 13% from last year and 16% below the 12-year average. Replenishment rates are also significantly lower than those set during the 2025 pumping season. However, after the 2022 crisis, absolute gas demand in Europe also decreased significantly, so this should be taken into account compared to previous years.
The market balance remains highly sensitive to any changes in the geopolitical outlook, but the fact that global LNG capacity will grow by 5.6% in 2026, supported by a 27% increase in production in the US and Canada, provides optimism.
Natural gas imports from Europe were at 1.65 million cubic meters per day (+ 0.05 million cubic meters from the previous week). Imports were present from Poland and Hungary. Exports from customs warehouses were present only to Moldova on August 10. Ukraine’s storage facilities contained 13.94 (+1.8%) billion cubic meters of natural gas. Withdrawals from underground storage facilities were almost non-existent, but there was injection - about 38 million cubic meters per day.