Gas price: Ukraine and Europe. Market overview April 20 - 24, 2026
In the "Medium and Long-Term Market" section of the UEEX, trading in the resource continued in April, May 2026. In total, positions for the sale or purchase of natural gas were formed by 9 companies: MC Ukrnaftoburinnia, GTS Operator of Ukraine, Ukrzaliznytsia, GSC Naftogaz Trading, etc. During the week, 2,430 thousand cubic meters of natural gas were sold in the section. The positions of the GTS Operator of Ukraine and Ukrzaliznytsia were successful. The sales prices were in the range of 22563.33 -24775 UAH/thousand cubic meters excluding VAT.
On the short-term natural gas market of the UEEX, participants formed orders on the within-day market and the day-ahead market. In total, 55 deals were concluded with a total volume of 4,020 thousand cubic meters.
During the week under review, European energy markets reflected developments in the Middle East. The weekend of April 18 and 19 witnessed chaos in the Strait of Hormuz, after Iranian Foreign Minister Abbas Araghchi announced on social media that the strait would be fully reopened. Ship tracking data indicated that 35 ships that set out changed course while initially attempting to cross the strait. Even the 27 successful crossings on April 18 were only a fraction of the normal traffic through the Strait of Hormuz, which is now effectively closed to traffic again.
At midnight GMT on Tuesday, April 21, the ceasefire agreement between the US and Iran expired. However, a few hours before its deadline, US President Donald Trump unilaterally announced an indefinite extension, saying that he had agreed to the request of Pakistani mediators and would "halt the attack on Iran until their leaders and representatives can offer a unified proposal." Despite this, Trump also said that the US Navy blockade of Iranian trade would continue. In response to the continued US blockade, the Iranian Navy seized two vessels in the strait on Wednesday afternoon, April 22. 15 LNG tankers remain blocked in the Persian Gulf, with no clear timetable for their release.
Friday’s upbeat trends were driven largely by rising risk sentiment in the Middle East. An extended ceasefire is due to expire on Sunday, while talks have stalled and the two sides appear unable to reach an agreement on control of the Strait of Hormuz.
Investment funds reduced their long positions in Dutch gas from 407 TWh to 398 TWh in the week ending April 10 to April 17.
Major repair work in Norway, with 50 million cubic meters of capacity unavailable to 70 million cubic meters of capacity by mid-May, puts pressure on the market.
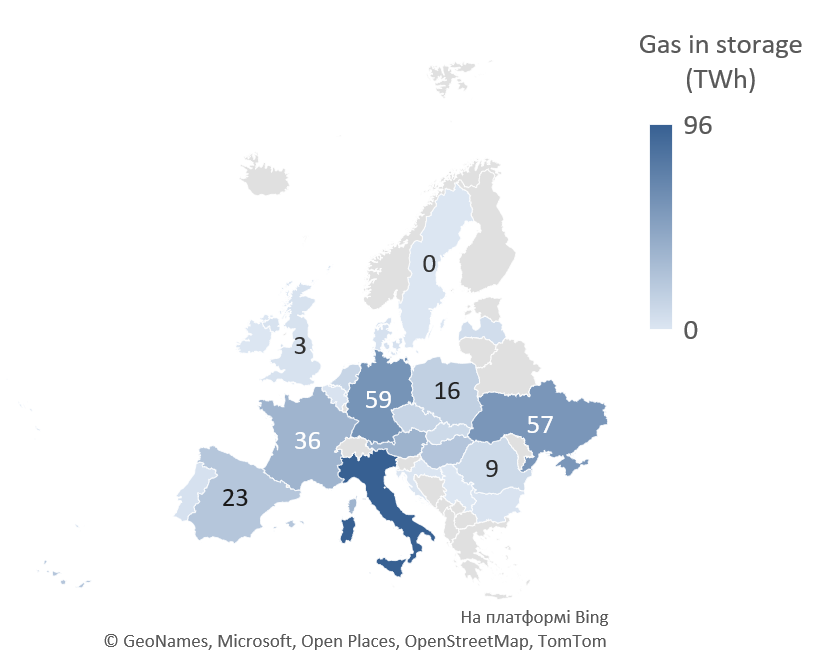
EU gas storage capacity is at 30%, currently 13% below the 5-year average, with global LNG supply disruptions during the peak summer pumping season set to increase as long as the strait remains blocked. The forward curve remains sensitive to Middle East risk sentiment amid concerns about low summer replenishment rates and a shortage of winter supplies.
The new Golden Pass facility in Texas has loaded its first LNG cargo, destined for Zeebrugge, providing a new alternative source of LNG supply. Expected growth in alternative global LNG supplies could limit growth in forward contracts.
Natural gas imports from Europe were at the level of 0.8-1.9 million cubic meters per day. Imports were present from Poland and Hungary. Exports from customs warehouses were also present to Poland and Hungary with a total volume of 0.6 million cubic meters per day, equally to both countries. Ukraine’s storage facilities contained 10.06 (+1%) billion cubic meters of natural gas. Withdrawals from underground storage facilities were practically absent, but small volumes of injection were observed - about 12 million cubic meters per day.